



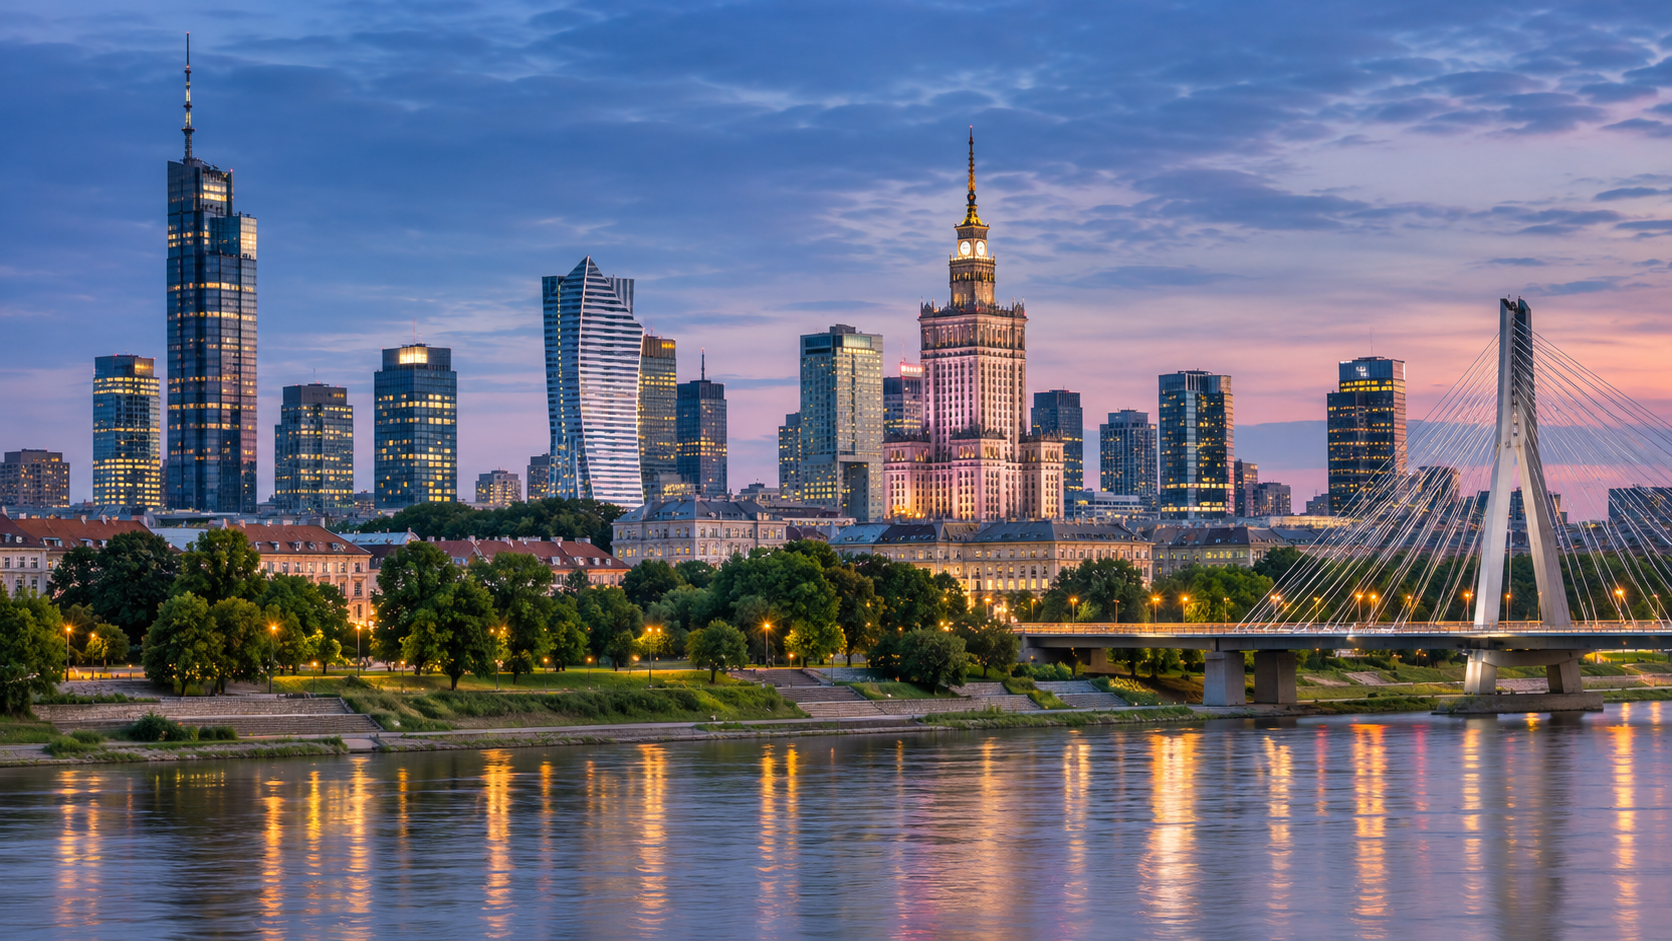
 Kraków · Poland
Submission received
Your information has been recorded by WONE.
Sourced guides to doing business in each market, and the status of every service there. Partners are in place in 39 markets so far.
One WONE Global Partner for each service in each market. Start from what you need to do, or go straight to a service.
Describe what you need. WONE Global names the service and the professional before any work begins.
Bring a requirement →Licences, value chains and the questions businesses in each industry ask first, with the services that usually apply.
What one country changes for the other, worked journeys step by step, and who handles each side.
When cross-border business becomes a dispute, UNIONE™, also part of the UNBOUNDED™ Global Ecosystem, prevents it, resolves it, arbitrates it and plans enforcement. 334 Fellows in 58 countries.
41 jurisdictions, each with primary sources and the date last checked.
Named senior professionals, each admitted as the one firm for a service in their country, and the firms they lead.
One Partner per service, per jurisdiction, admitted by review against published criteria.
Every statement is labelled: source-checked, professionally reviewed or not yet checked, with its source and date where checked.
Answers cite WONE Global's sourced statements and show how each one was checked. Research, not advice.
Accomplished regional specialists and international cross-border intelligence, across 100 countries, with one contact and one published Standard.
Central & Eastern Europe · WONE Global market
Poland is covered by WONE for cross-border business discovery, with links to relevant expertise, professionals, industries and market intelligence. 3 of 18 services have a WONE Global Partner here. For the others, WONE Global confirms availability on request.
Warsaw · Sunday 15 November
01:42
Local time
Market guide · Source-checked research
Poland is an EU member state with a civil-law system where most foreign investors use a limited liability company (sp. z o.o.), which needs PLN 5,000 share capital and is registered in the National Court Register, including online through the S24 system. Corporate income tax is 19%, with 9% for small and new taxpayers, and VAT is 23%. Structured e-invoicing through KSeF became mandatory in stages during 2026. Tax incentives for new investments are available across the country through the Polish Investment Zone.
Essentials guide · Source-checked research100% of statements checked against a source41 checked against an official source7 checked against a secondary sourceChecked 2026-10-19Not yet professionally reviewed
Poland has a codified civil-law system. Companies come into existence on entry in the National Court Register (KRS), kept by registry courts under the Ministry of Justice, and beneficial owners are reported to the Central Register of Beneficial Owners. Tax is administered by the National Revenue Administration under the Ministry of Finance; competition and merger control sits with UOKiK, data protection with UODO, industrial property with the Patent Office (UPRP) and financial supervision with the KNF. As an EU member state, Poland applies EU rules on customs, free movement of capital, data protection and cross-border enforcement of judgments.
Key facts
Foreign investors commonly use a limited liability company (sp. z o.o.), a joint stock company or a branch. Companies are registered in the National Court Register, which also triggers tax and statistical numbers, and beneficial owners must be reported to the CRBR.
Key facts
A sp. z o.o. needs at least PLN 5,000 share capital; a joint stock company needs PLN 100,000, and a branch has no minimum capital.
Using the online S24 template shortens the registry court's statutory examination period from 7 days to 1 day, which matters when timing a launch.
KRS entry leads to issue of the NIP tax number and REGON statistical number, so registration and tax onboarding are linked.
A branch is registered in the KRS under the foreign company's name with branch in Poland added; a representative office can only do representation and marketing.
Every company and partnership must report its ultimate beneficial owners to the CRBR.
Who handles this in PolandCorporate & Entity ServicesLegal & Contracting · Andrzej Zacharzewski
Questions on this topic
6 statements on entry, investment and company formation in Poland
Corporate income tax is 19%, with a 9% rate for small and new taxpayers, and VAT is 23% with reduced rates. Non-resident income such as interest, royalties and certain services is taxed at 20% subject to treaties. Pillar Two top-up taxation applies to large groups from 2025 and KSeF e-invoicing became mandatory in 2026.
Key facts
The standard CIT rate is 19%; the 9% rate depends on revenue thresholds in EUR converted to PLN.
Payments of interest, royalties, know-how and advisory or legal service fees to non-residents attract 20% tax unless a treaty reduces it, so treaty documentation matters before payment.
VAT is 23% standard, with 8% and 5% reduced rates for listed goods and services.
KSeF structured e-invoicing applies to large taxpayers from 1 February 2026, to most others from 1 April 2026 and to the smallest from 1 January 2027.
Groups with revenue of EUR 750 million or more are within Pillar Two top-up taxation from 1 January 2025.
Who handles this in PolandTax & International StructuringAccounting, Reporting & Statutory Compliance
Questions on this topic
6 statements on tax, accounting and statutory reporting in Poland
The 2026 minimum wage is PLN 4,806 gross a month and employer social security costs add roughly a fifth to gross pay. EU and EEA nationals work on the same footing as Poles, while other foreigners need one of several permit routes.
Key facts
Minimum pay from 1 January 2026 is PLN 4,806 a month or PLN 31.40 an hour gross.
Employer social security contributions run at about 19.48% to 22.14% of gross salary, with a 2026 cap on the pension and disability part.
EU and EEA nationals are treated as Polish nationals for employment, so permit planning focuses on non-EU staff.
Non-EU staff can work under work permits, seasonal permits, combined residence and work permits or a declaration on entrusting work; visa-free nationals of Colombia, Georgia and Venezuela cannot work.
The Labour Code has regulated remote work since 7 April 2023.
Who handles this in PolandEmployment, Payroll & Mobility
Questions on this topic
6 statements on employment, payroll and mobility in Poland
The Polish Investment Zone offers a CIT or PIT exemption for new investments anywhere in Poland for 12 to 15 years, and government grants are available for some projects. Sector licensing, public procurement and foreign real estate rules were not confirmed in this review.
Key facts
Tax exemptions under the Act of 10 May 2018 on support for new investments are available nationwide, not only in former special economic zones.
Support decisions run for 12 to 15 years depending on regional aid intensity.
Decisions are issued on behalf of the economy minister through the Special Economic Zone managing companies, which are the practical point of contact.
PAIH helps investors apply for state budget grants for new investments.
Who handles this in PolandGovernment & Regulatory AffairsTax & International Structuring
Questions on this topic
4 statements on licensing, sector rules and real estate in Poland
As an EU member state Poland may not restrict capital movements or payments, subject to Treaty exceptions. The KNF supervises the financial market and GIIF is the financial intelligence unit under the 2018 AML Act, which shapes bank onboarding checks.
Key facts
EU law prohibits restrictions on capital movements and payments, including with non-EU countries, which limits the scope for exchange controls on profit repatriation.
Banks and other financial institutions are supervised by the KNF.
GIIF sits at the centre of the AML system under the Act of 1 March 2018, which drives the know-your-customer checks banks apply.
The currency is the Polish złoty, with NBP publishing reference exchange rates.
Who handles this in PolandBanking & Capital AccessPayments, Foreign Exchange & SettlementRisk, Compliance & Financial Integrity
Questions on this topic
4 statements on banking, payments and capital flows in Poland
Poland is part of the EU customs union and applies the Union Customs Code and EU export control rules. Exports and intra-EU supplies of goods are zero-rated for VAT.
Key facts
Customs rules for goods entering or leaving Poland are set by the Union Customs Code and apply uniformly across the EU.
Exports of listed dual-use items need an authorisation under EU Regulation 2021/821.
Goods exports and intra-EU supplies are zero-rated for VAT, subject to conditions.
Who handles this in PolandTrade, Customs & Supply Chain
Questions on this topic
3 statements on customs, trade and product rules in Poland
The GDPR applies directly and is enforced by UODO, which takes breach notifications in Polish. Tax digitalisation adds technical obligations such as KSeF e-invoicing and electronic JPK_CIT ledgers.
Key facts
UODO is the supervisory authority and applies the GDPR.
Breaches should be notified where feasible within 72 hours, in Polish, through biznes.gov.pl, ePUAP or post.
Books must be kept electronically and reported as JPK_CIT; the first reporting date for the 2025 tax year may have moved.
Who handles this in PolandTechnology, Data & Cyber
Questions on this topic
4 statements on data protection, cyber security and e-invoicing in Poland
UPRP registers patents, utility models, trademarks and designs under the Industrial Property Law of 2000. Poland is in the Madrid, PCT and Paris systems, and EU trade marks also cover Poland.
Key facts
National rights are filed with UPRP, which also decides trademark oppositions.
International filings can designate Poland under the Madrid Protocol (since 1997) and the PCT (since 1990).
An EU trade mark covers Poland and all other EU states with one application.
Who handles this in PolandIntellectual Property & Brand Protection · Andrzej Zacharzewski
Questions on this topic
5 statements on intellectual property and brand protection in Poland
Deals meeting UOKiK turnover thresholds need clearance before closing, with fines for gun-jumping. Poland may also screen foreign investment under the EU framework, but the national rules were not confirmed here.
Key facts
Notification is required where combined turnover exceeded EUR 1 billion worldwide or EUR 50 million in Poland, subject to exemptions.
Closing before clearance can cost up to 10% of turnover, so deal timetables need a clearance condition.
Phase 1 review lasts up to one month, with up to four more months for complex cases.
The EU FDI Screening Regulation allows national screening of foreign investment on security or public order grounds.
Who handles this in PolandTransactions & DealsGovernment & Regulatory Affairs
Questions on this topic
4 statements on m&a, merger control, investment screening and insolvency in Poland
The 2024 whistleblower act requires internal reporting channels for entities with 50 or more workers and for all financial sector entities. Anti-bribery and sanctions rules were not confirmed in this review.
Key facts
Entities with at least 50 people working for them must have an internal whistleblowing procedure.
Financial sector entities need reporting channels whatever their size.
External reports go to the RPO, which forwards them to the competent authority.
Who handles this in PolandRisk, Compliance & Financial Integrity
Questions on this topic
3 statements on anti-bribery, compliance and supply-chain duties in Poland
Poland has applied the New York Convention since 1962 with reciprocity and commercial reservations. Judgments from other EU states are enforced without exequatur under Brussels I bis, and the HCCH 2019 Judgments Convention applies through the EU.
Key facts
Foreign arbitral awards from other contracting states are enforceable under the New York Convention.
EU judgments in civil and commercial matters are recognised and enforced without a declaration of enforceability.
Judgments from other HCCH 2019 Convention parties can be recognised since 1 September 2023.
Who handles this in PolandDisputes & Resolution · Andrzej ZacharzewskiLegal & Contracting · Andrzej Zacharzewski
Questions on this topic
3 statements on courts, arbitration and enforcement in Poland
Sources last checked on 19 October 2026. None of it has been professionally reviewed yet: it is research checked against official and secondary sources by WONE Global, not legal or tax advice.
WONE Global Intelligence
Ask in your own words. Answers come from WONE Global's checked records, with every source shown, and end with the named Partner who can act. Go deeper on any point, or build a decision file.
WONE Global Partners
3 of 18 services have a WONE Global Partner in Poland. For the other 15, WONE Global confirms whether a vetted Associate firm can act and tells you who it is before any work starts.
WONE Global Partners
Senior professionals responsible for WONE Global work in Poland, under their own professional rules.
Kraków · Poland Kraków · Poland
WONE Global Partner · Poland
Legal Adviser. Co-founder of the Firm. Has been advising parties on technology contracts for more than a dozen years. Specialises in intellectual property law and new technologies. Provides day-to-day legal services to …
What changed recently
From the Newsroom: changes recorded in this guide, each checked against its official source, with the date it takes effect.
Cases
Cases whose typical case runs through Poland, each with what is at stake, how WONE Global handles it and who handles it here.
Situations
Common problems that need someone on the ground, and worked scenarios involving Poland.
Worked scenarios
Scenarios are representative of the work WONE Global coordinates, not specific client matters.
UNBOUNDED™ · Global Business Circuit™
Doing business in Poland, across the year
Circuit sessions are 60 minutes online, with 12 business leader places and one corridor. The leaders' own questions set the agenda.
WONE Global is one of the six institutions of the UNBOUNDED™ Global Ecosystem. Links open unboundedglobal.com. WONE Global in the ecosystem
Save your questions, decisions and WONE activity in one account.
Forgot your password? Reset it securely.
Partner workspaces are for Partner firms. Explore partnership →