




 Douala · Cameroon

Submission received
Your information has been recorded by WONE.
Sourced guides to doing business in each market, and the status of every service there. Partners are in place in 37 markets so far.
One WONE Global Partner for each service in each market. Start from what you need to do, or go straight to a service.
Describe what you need. WONE Global names the service and the professional before any work begins.
Bring a requirement →Licences, value chains and the questions businesses in each industry ask first, with the services that usually apply.
What one country changes for the other, worked journeys step by step, and who handles each side.
When cross-border business becomes a dispute, UNIONE™, also part of the UNBOUNDED™ Global Ecosystem, prevents it, resolves it, arbitrates it and plans enforcement. 334 Fellows in 58 countries.
41 jurisdictions, each with primary sources and the date last checked.
Named senior professionals, each admitted as the one firm for a service in their country, and the firms they lead.
One Partner per service, per jurisdiction, admitted by review against published criteria.
Every statement is labelled: source-checked, professionally reviewed or not yet checked, with its source and date where checked.
Answers cite WONE Global's sourced statements and show how each one was checked. Research, not advice.
Accomplished regional specialists and international cross-border intelligence, across 100 countries, with one contact and one published Standard.
Service · Trade and deals
Buying, selling and investing across borders, from the first structure to closing and after. Led by a WONE Global Partner where one is named. Elsewhere, WONE Global confirms on request whether a vetted Associate firm can act.
Professional knowledge centre
Cross-border deals rarely fail on price; they slip on approvals, employees and taxes that differ country by country. A buyer must map every merger control and foreign investment filing triggered by either group's sales and activities, decide whether a share or asset structure works in each market, and plan for employees who move automatically in an asset sale. Recent changes have raised the stakes: India, Germany and COMESA now catch high-value deals for targets with low local turnover, the US HSR thresholds rose for 2026, France raised its merger thresholds from 1 September 2026, and the EU adopted a revised foreign investment screening regulation in June 2026. Takeover codes in the UK and Singapore were also amended in 2026.
Source-checked research99% of statements checked against a source88 checked against an official source17 checked against a secondary sourceChecked 2026-10-19Not yet professionally reviewed
Approvals fall into two families. Merger control asks whether the deal harms competition and is triggered by turnover, assets, market share or deal value. Foreign investment screening asks whether the buyer or the target's activities raise security concerns, and is triggered by sector and shareholding with no turnover test. Both families are often suspensory, so the longest review sets the closing timetable.
Structure and people decisions follow. In an asset deal the EU Acquired Rights Directive, UK TUPE and Germany's section 613a move employees automatically; in a share deal transfer taxes may still apply, especially where the target owns real estate. For listed targets, takeover codes add mandatory offer thresholds from 25% to 40% and fixed timetables. The modules below compare the rules in India, the UAE, Saudi Arabia, Singapore, the UK, the US, Germany and France, with EU and COMESA instruments where they apply.
Merger control decides whether a deal must be cleared by competition authorities before it closes. Each regime has its own turnover, asset, market-share or deal-value tests, and several now catch acquisitions of targets with little local turnover but a high price. Most of the regimes covered here are suspensory, so closing before clearance can make the deal ineffective or attract fines of up to 10% of turnover. A multi-country deal needs a filing analysis for every country where either side has sales or assets, done before the timetable is fixed.
Questions on this topic
31 statements on merger control thresholds
Foreign investment screening runs alongside merger control but asks a different question: whether the buyer's identity or the target's activity raises national security or public order concerns. Thresholds are low (often 10% to 25% of votes), there is usually no turnover test, and several regimes make an unapproved deal void or provisionally ineffective. The EU adopted a revised screening regulation in June 2026 that will require every Member State to screen deals in core sensitive sectors once it applies.
Questions on this topic
23 statements on foreign investment approval in deals
When a business is sold as a going concern, employment protection rules in the EU and the UK move the employees, their terms and much of their history to the buyer automatically, and prevent dismissals because of the transfer. Information and consultation duties apply before completion and failures can be penalised. Outside Europe the rules are different and often less developed, so each country in a carve-out needs its own analysis.
Questions on this topic
16 statements on employees on a sale, 1 not yet checked against a source
Transfer taxes are charged on the transfer itself, regardless of whether the seller makes a gain, and they often fall on the buyer. Share transfers usually attract lower rates than direct transfers of real estate, but several countries treat the sale of a property-rich company as a property transfer. Rates, payers and deadlines differ, and in India and Germany state-level rules add a further layer.
Questions on this topic
13 statements on transfer taxes and stamp duty
Buying a listed company brings rules that do not apply to private deals: mandatory offers when a control threshold is crossed, minimum offer periods, disclosure of stakes and regulator approval of offer documents. The thresholds differ: 25% in India, 30% in the UK and Germany, 40% for private transactions in Saudi Arabia, and stake disclosure above 5% in the United States. Singapore amended its Code in July 2026 and the UK Code was amended in February 2026.
Questions on this topic
17 statements on public takeover rules
Worked example, from official sources
A non-EU buyer is acquiring 100% of a private target group that sells in the UK, Germany, India and Saudi Arabia. Which merger control filings are needed, and which foreign investment approvals should be checked?
| Country | Test applied | Facts | Outcome | Official or cited source |
|---|---|---|---|---|
| EU | EUR 5,000m / EUR 2,500m worldwide tests | Combined below EUR 2,500m | No EU dimension; national rules apply | European Commission, Mergers: Procedures |
| Germany | EUR 500m worldwide; EUR 50m and EUR 17.5m in Germany | EUR 120m and EUR 40m in Germany | Notifiable; standstill applies | Bundeskartellamt; GWB |
| United Kingdom | Target turnover over GBP 100m; 25% share of supply; hybrid test | GBP 60m target turnover; share below 25% | Outside CMA jurisdiction on these facts | Enterprise Act 2002 s23; CMA guidance |
| India | Small-target exemption; deal value over Rs 2,000 crore with substantial Indian operations | Indian turnover Rs 600 crore, about 22% of global and over Rs 500 crore; deal value over Rs 2,000 crore | Notifiable under the deal-value threshold | Competition Act s5(d); CCI Combinations Regulations 2024 |
| Saudi Arabia | SAR 200m worldwide; SAR 40m target; SAR 40m Saudi | SAR 80m Saudi sales from target | Notifiable at least 90 days before completion; fee 0.02% capped at SAR 250,000 | GAC rules (secondary summary) |
| COMESA | USD 60m combined in the Common Market | No COMESA sales | Not notifiable | Law-firm summary of 2025 Regulations |
Result on these facts
On these facts three filings are needed: Germany, India (through the deal-value test) and Saudi Arabia, with Saudi Arabia's 90-day pre-completion filing likely to set the earliest closing date. There is no EU dimension, no CMA jurisdiction and no COMESA filing. Foreign investment filings depend on the target's activities and the buyer's ownership chain and must be checked separately.
Confirm turnover figures under each regime's calculation rules, the current Saudi GAC guidelines (the figures here come from a secondary practice guide), the UK share of supply and whether a voluntary CMA briefing is advisable, and any national rules in other countries where either group has sales.
Each statement is numbered to the source it was checked against. We use official sources where we can, and each statement says whether it was checked against an official or a secondary source. Sources last checked on 19 October 2026. None of it has been professionally reviewed yet: it is research checked against official and secondary sources by WONE Global, not legal or tax advice.
A concentration has an EU dimension where the combined worldwide turnover of all undertakings concerned exceeds EUR 5,000 million and at least two of them each have EU-wide turnover above EUR 250 million. Council Regulation (EC) No 139/2004, Article 1(2). Not met if each undertaking achieves more than two-thirds of its EU-wide turnover in one and the same Member State.
A concentration also has an EU dimension where combined worldwide turnover exceeds EUR 2,500 million, combined turnover exceeds EUR 100 million in each of at least three Member States, at least two undertakings each have more than EUR 25 million in each of those three Member States, and at least two each have EU-wide turnover above EUR 100 million. Article 1(3) of Regulation 139/2004. The same two-thirds rule applies.
A concentration must be notified to the Bundeskartellamt if, in the last business year, the parties' combined worldwide turnover exceeded EUR 500 million, one party had German turnover above EUR 50 million and another party had German turnover above EUR 17.5 million. All three conditions must be met. Concentrations with an EU dimension are reviewed by the European Commission instead.
Reused from de-transactions-001.
A notifiable merger may not be implemented before clearance or expiry of the review periods, and transactions that breach this prohibition are legally ineffective. Exceptions include land transactions entered in the land register and corporate measures entered in the commercial register, and cases later resolved under § 41(1) sentence 3 GWB.
Reused from de-transactions-005.
The CMA has jurisdiction over a merger where the UK turnover of the target exceeds £100 million. Threshold in force from 1 January 2025 under the Digital Markets, Competition and Consumers Act 2024 amendments.
Reused from gb-transactions-007.
The share of supply test is met where the merging parties together supply or acquire 25% or more of goods or services of a particular description in the UK or a substantial part of it, the merger increases that share, and at least one party has UK turnover above £10 million.
Reused from gb-transactions-008.
A hybrid test gives the CMA jurisdiction where one party supplies or acquires at least 33% of goods or services of any description in the UK and has UK turnover above £350 million, and another party has a UK nexus. Designed to catch acquisitions of small or pre-revenue targets by large firms. In force from 1 January 2025.
Reused from gb-transactions-009.
Under the Competition (Minimum Value of Assets or Turnover) Rules 2024, a combination does not need to be notified where the target has assets in India of not more than Rs 450 crore or turnover in India of not more than Rs 1,250 crore. Small target (de minimis) exemption; does not apply where the deal value threshold is met.
Effective date from secondary source; the CCI newsletter gives the figures but not the date. Reused from in-transactions-002.
A transaction whose value exceeds Rs 2,000 crore is notifiable to the CCI where the target has substantial business operations in India. Section 5(d) of the Competition Act inserted by the Competition (Amendment) Act 2023; in force from 10 September 2024; applies even where the small target exemption would otherwise apply. Value includes direct, indirect, immediate and deferred consideration; if it cannot be established with reasonable certainty the threshold is deemed met.
Also confirmed in the Competition (Amendment) Act 2023 on the CCI website. Reused from in-transactions-003.
A target has substantial business operations in India if, for digital services, 10% or more of its global users are in India, or, for other businesses, its Indian gross merchandise value or turnover is 10% or more of the global figure and above Rs 500 crore. CCI (Combinations) Regulations 2024, in force 10 September 2024. The Rs 500 crore floor does not apply to digital services.
Measurement periods for users, GMV and turnover are set in the Regulations and were not verified here. Reused from in-transactions-004.
An economic concentration must be notified to the General Authority for Competition (GAC) where the participating undertakings' combined worldwide annual sales exceed SAR 200 million, the target's worldwide annual sales exceed SAR 40 million and the parties' combined sales in Saudi Arabia exceed SAR 40 million. The target must contribute to the Saudi sales figure. For mergers and joint ventures, at least two parties must each have worldwide sales above SAR 40 million. The combined threshold was raised from SAR 100 million by a GAC decision of 15 March 2023.
Secondary (law firm) source; GAC's website and the Bureau of Experts legislation portal block automated access, so GAC's implementing regulations and guidelines could not yet be checked. Reused from sa-transactions-g01.
A notifiable concentration must be filed with GAC at least 90 days before completion and may not close until GAC approves it in writing, unless GAC's 90-day review period, which starts when the filing is complete, lapses without a decision. The review period can be suspended while GAC requests information; lapse of the period is treated as approval.
Secondary (law firm) source; GAC's website and the Bureau of Experts legislation portal block automated access, so GAC's implementing regulations and guidelines could not yet be checked. Reused from sa-transactions-g02.
The GAC filing fee is 0.02% of the total annual sales of the undertakings participating in the concentration, capped at SAR 250,000.
Secondary (law firm) source; GAC's website and the Bureau of Experts legislation portal block automated access, so GAC's implementing regulations and guidelines could not yet be checked. Reused from sa-transactions-g03.
Under the COMESA Competition and Consumer Protection Regulations 2025, a merger is notifiable where the combined annual turnover or asset value of all parties in the COMESA Common Market equals or exceeds USD 60 million and at least two parties each have turnover or assets of USD 10 million or more in the Common Market. COMESA regional regime. Not notifiable where each party achieves at least two-thirds of its aggregate turnover or assets in one and the same Member State. The previous combined threshold was USD 50 million.
Secondary source: the official COMESA Competition Commission text could not yet be checked, and a second law-firm briefing (DLA Piper) could not yet be checked because the site returned HTTP 429. Confirm against the Regulations and Rules as published by the COMESA Competition Commission.
No relevant merger situation arises if none of the enterprises concerned has UK turnover above £10 million (small merger safe harbour).
Reused from gb-transactions-010.
The CCI must form a prima facie opinion on a combination within thirty days of notice, and a combination is deemed approved if no order is passed within one hundred and fifty days of notice. Sections 29(1B), 6(2A) and 31(6) of the Competition Act as amended by the Competition (Amendment) Act 2023 (previously 210 days).
Commencement date for these provisions per CCI Fair Play Volume 50. Reused from in-transactions-005.
Acquisitions of certain entities active in 17 sensitive areas of the economy, including defence, energy and transport, must be notified to and approved by the government before completion under the National Security and Investment Act 2021. Applies regardless of the acquirer's nationality, including UK acquirers. There is no turnover threshold.
Reused from gb-transactions-001.
The government can call in a non-notified acquisition for assessment up to 5 years after it took place, and within 6 months of becoming aware of it. Applies to qualifying acquisitions that were not notified.
Reused from gb-transactions-004.
Under the Foreign Trade and Payments Ordinance (AWV), a non-EU acquirer's direct or indirect voting share in a German company triggers cross-sector investment review at 10% for the most sensitive categories in § 55a(1) nos. 1–7, 20% for categories nos. 8–27, and 25% for all other companies. Further acquisitions are reviewable when the holding reaches 20%, 25%, 40%, 50% or 75% (depending on category). Atypical control through board seats, vetoes or information rights is treated as reaching the threshold.
Reused from de-transactions-007.
An entity of a country sharing a land border with India, or an investment whose beneficial owner is linked to such a country, can invest only under the government route, and a later transfer that brings beneficial ownership within this category also needs government approval. Press Note 3 (2020 Series) dated 17 April 2020, as revised in 2026; subject to the 10% non-controlling exception in in-establish-004. Central rule.
The FAQ uses the 2020 wording (beneficial owner situated in or a citizen of such a country). Secondary sources report that Press Note 2 (2026 Series) dated 15 March 2026 removed the 'situated in' limb so the test now turns on citizens and entities of those countries; the official Press Note text could not yet be checked. Reused from in-establish-003.
A foreign investor must obtain MISA's approval before engaging in an activity on the list of excluded activities, and before a change in ownership of an investment in a restricted activity. Activities on the list of excluded (prohibited or restricted) activities.
Reused from sa-transactions-g13.
Failing to notify a concentration or closing before clearance can be fined up to 10% of total annual sales, or up to SAR 10 million where sales cannot be estimated. GAC fined each party SAR 400,000 in a 2024 case for implementing a notifiable concentration without notification. A settlement route can impose up to three times the gains from the violation.
Secondary (law firm) source; GAC's website and the Bureau of Experts legislation portal block automated access, so GAC's implementing regulations and guidelines could not yet be checked. Reused from sa-transactions-g04.
Failure to notify a notifiable combination can attract a penalty of up to one per cent of the total turnover or assets, or of the value of the transaction, whichever is higher. Section 43A of the Competition Act as substituted by the Competition (Amendment) Act 2023.
Reused from in-transactions-007.
A notifiable acquisition completed without approval is void. Civil and criminal penalties can also apply; civil penalties of up to 5% of worldwide turnover or £10 million, whichever is greater.
Reused from gb-transactions-003.
WONE Global Intelligence
Ask in your own words. Answers come from WONE Global's checked records, with every source shown, and end with the named Partner who can act. Go deeper on any point, or build a decision file.
Scope
Key questions
You don’t need the answers before you talk to us. Working through them is the first thing we do together.
Coverage
A named WONE Global lead in 17 markets today. In every other featured market, WONE Global arranges qualified local expertise on request and tells you who it is before work begins.
 CameroonLed by Edmond Christian AKOA MBALLA
 ChinaLed by Roberto Gilardino
ColombiaLed by Katherin Diaz Velilla
 GermanyLed by Ulrike Berner, MBA
 Hong KongLed by Yvonne Chow
 IsraelLed by Karin Horev
 ItalyLed by Alessandro Dagnino
 LuxembourgLed by Bruno Abbate
 MexicoLed by Miguel Angel Asencio Asencio
 MoroccoLed by Mouad Aktaou
PanamaLed by Ebrahim Asvat K.
 PortugalLed by Bruna Prinzo
 RwandaLed by Lydie N. Murorunkwere
 South AfricaLed by Kameel Keshav
 SwitzerlandLed by Gianmatteo Terruzzi
 United StatesLed by Frederick Miles Adler
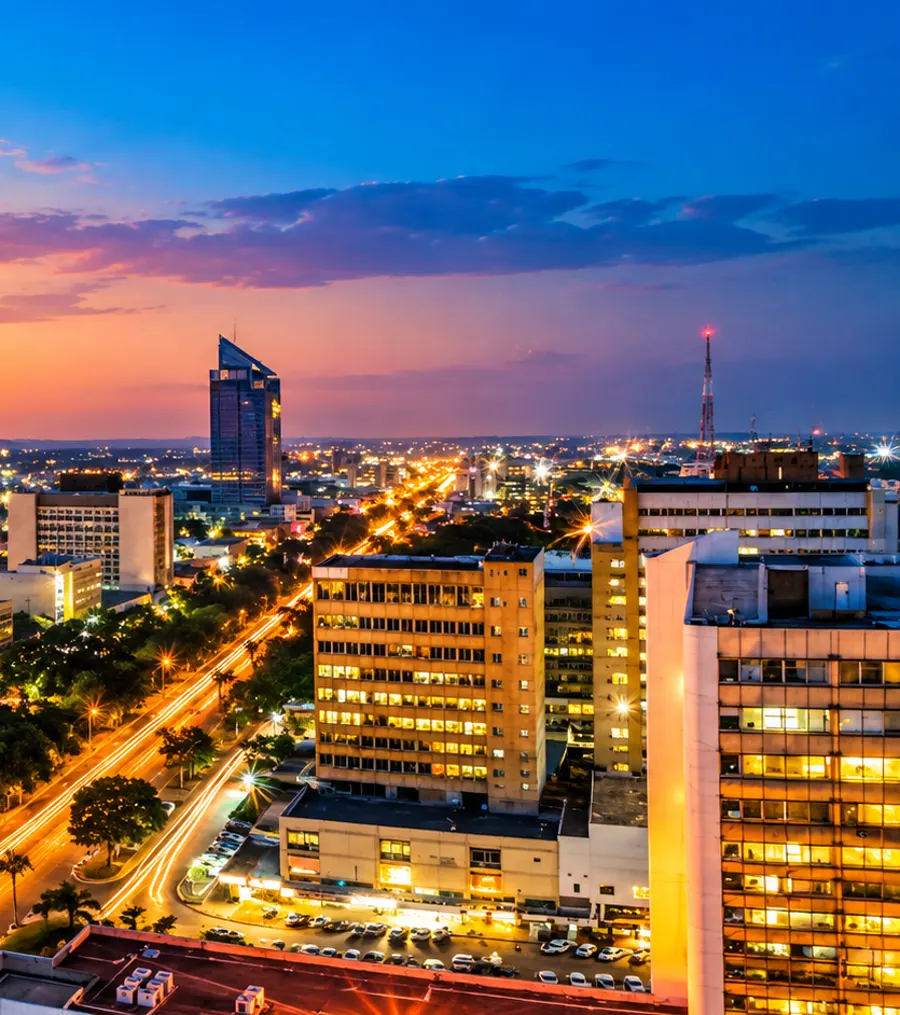 ZambiaLed by Reagan Blankfein Gates
WONE Global Partners
Each is responsible for this service in their own jurisdiction, under their own professional rules.
Douala · Cameroon Shanghai · China
WONE Global Partner · China
Roberto Gilardino is Regional Partner at Horizons, supervising the advisory’s activities in North Asia as well as additional countries (including Mongolia, Malaysia, Indonesia, Pakistan, UAE, Cyprus and Malta).
 Bogotá · Colombia
WONE Global Partner · Colombia
Complete profile
<span style="color: #000000;font-size: medium">International tax attorney and strategic advisor with 12+ years across Colombia\\\'s DIAN, Ministry of Finance, Senate, Presidency, and EY. Co-founder of V&V Asociados. Spe…
 Munich · Germany
 Kowloon · Hong Kong
WONE Global Partner · Hong Kong
Ms. Chow, our director, graduated from Smith College (US), and obtained her master\'s degree in Religion from Yale University. She is an associate member of Hong Kong Institute of Certified Public Accountants and Instit…
 Tel Aviv · Israel
WONE Global Partner · Israel
Adv. Karin Horev has been practicing corporate and commercial law for more than 20 years, with a focus on complex technology-related matters. Over the years, Karin has led a large number of complex and wide-ranging tran…
 Rome · Italy
 Luxembourg · Luxembourg
WONE Global Partner · Luxembourg
 Mexico City · Mexico
WONE Global Partner · Mexico
Complete profile
<p style="line-height: normal;margin-top: 0pt;margin-bottom: 0pt;margin-left: .2in;text-indent: -.19in;text-align: left;direction: ltr"><span style="font-size: 18.0pt;font-family: Arial;color: #415364">Miguel has more t…
 Casablanca · Morocco
WONE Global Partner · Morocco
 Panamá · Panama
WONE Global Partner · Panama
Ebrahim Asvat K. is a founding partner of Patton, Moreno & Asvat. His practice focuses on corporate law, asset and tax planning, mergers and acquisitions, and offshore business structures. He holds an LL.M. from Harvard…
 Lisbon · Portugal
WONE Global Partner · Portugal
 Kigali · Rwanda
WONE Global Partner · Rwanda
Lydie is the Founder and Managing Director of ML Corporate Services Ltd and the first Chairperson of the Rwanda Trust Companies Association (RTCA).
WONE Global Partner · South Africa
Corporate finance, M&A, capital markets, strategic advisory and board governance professional.
 Lugano · Switzerland
 South Carolina · United States
WONE Global Partner · United States
 Lusaka · Zambia
WONE Global Partner · Zambia
Complete profile
Reagan started his career in practice at Mainza & Company where he had interned while pursuing a bar qualification at the Zambia Institute of Advanced Legal Education (ZIALE) in 2008. Upon being called to the bar, Reaga…
Who does what
WONE Global is not a law, tax or audit firm. Each firm is independent and regulated where it practises.
Cases
The cases this service leads or joins, in the words clients use. Each sets out what is at stake, how WONE Global handles it and who handles it in each market.
Contact WONE Global
Save your questions, decisions and WONE activity in one account.
Forgot your password? Reset it securely.
Partner workspaces are for Partner firms. Explore partnership →