




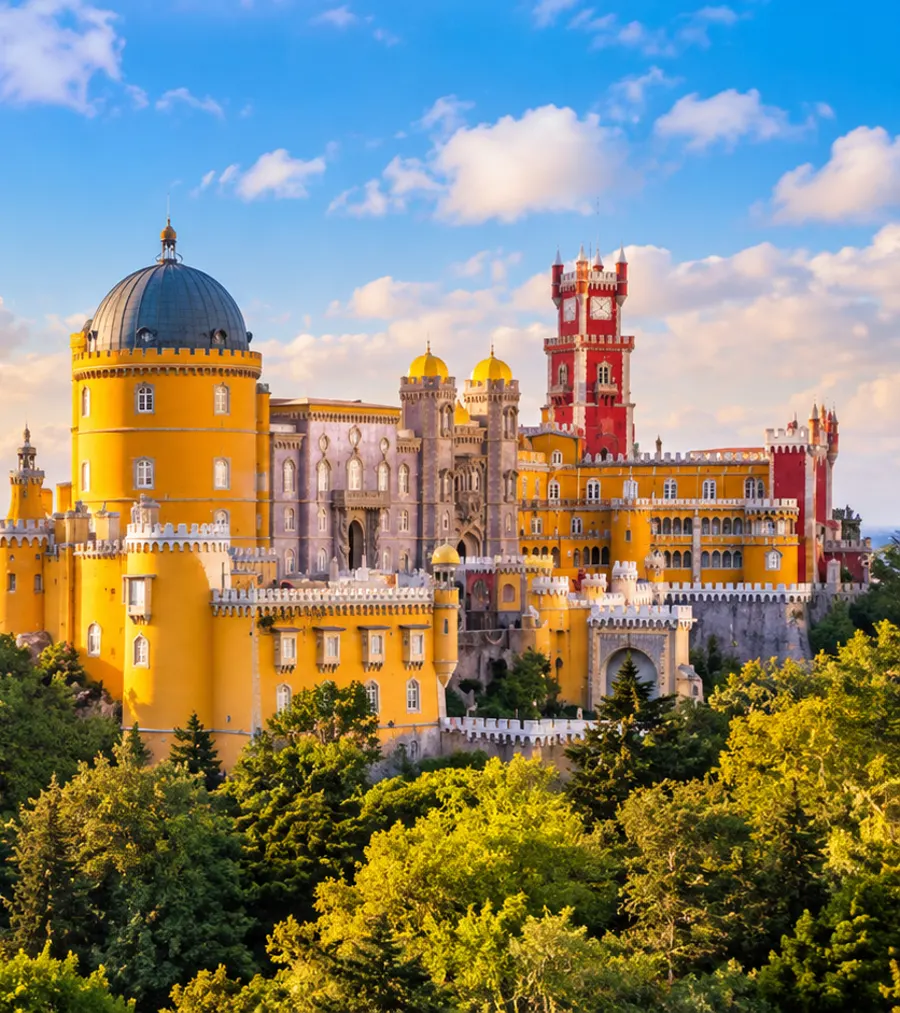
 Lisbon · Portugal
WONE Global Capability Partner · Portugal
Sourced guides to doing business in each market, and the status of every service there. Partners are in place in 35 markets so far.
One WONE Global Partner for each service in each market. Start from what you need to do, or go straight to a service.
Licences, value chains and the questions businesses in each industry ask first, with the services that usually apply.
Ask WONE Global what applies to your industry in a market, with the sources shown.
What one country changes for the other, worked journeys step by step, and who handles each side.
Named senior professionals, each admitted as the one firm for a service in their country, and the firms they lead.
One Partner per service, per jurisdiction, admitted by review against published criteria.
Every statement is labelled: source-checked, professionally reviewed or not yet checked, with its source and date where checked.
Answers come from statements checked against official sources, with the sources shown. Research, not advice.
Accomplished regional specialists and international cross-border intelligence, across 100 countries, with one contact and one published Standard.
Western Europe · WONE Global market
Portugal is covered by WONE for cross-border business discovery, with links to relevant expertise, professionals, industries and market intelligence. 1 of 18 services have a WONE Global Partner here. For the others, WONE Global confirms availability on request.
Lisbon · Saturday 24 October
04:42
Local time
Market guide · Source-checked research
Portugal is an EU member state with a civil law system and few restrictions on foreign investors, who usually set up a private limited company with minimal capital or a branch. Corporate income tax is 19 percent on the mainland in 2026, legislated to fall to 17 percent by 2028, plus municipal and state surtaxes; VAT is 23 percent. Profits can be repatriated without limits. The 2026 minimum wage is EUR 920 a month.
Essentials guide · Source-checked research100% of statements checked against a source23 checked against an official source23 checked against a secondary sourceChecked 2026-10-19Not yet professionally reviewed
Portuguese company formation runs through the commercial registry, with fast counter and online routes, and beneficial owners must be declared in the RCBE. Tax is administered by the Tax and Customs Authority, with lower rates in Madeira and the Azores. As an EU member, Portugal applies EU customs, data protection and sanctions law. Key bodies include AICEP for investment, the Competition Authority (AdC), CNCS for cybersecurity and INPI for industrial property. Several areas rely on secondary sources because official pages could not be reached run.
Key facts
Portugal has few restrictions on foreign investors and no local partner requirement. Private limited companies can be formed with minimal capital, at a counter or online, and must register within 10 days and declare beneficial owners within 30 days.
Key facts
A single-member private limited company needs EUR 1 capital and a multi-partner one EUR 2; a public limited company needs EUR 50,000.
No Portuguese partner is required, and a branch is available without creating a new entity.
Empresa na Hora (EUR 360) and Empresa Online 2.0 (from EUR 220) offer fast formation.
Register within 10 days; the company binds third parties only after registration.
Declare beneficial owners in the RCBE within 30 days of registration.
Who handles this in PortugalSetting up and running a companyContracts and commercial law
Questions on this topic
6 statements on entry, investment and company formation in Portugal
Corporate income tax (IRC) is 19 percent on the mainland in 2026 and legislated to fall to 17 percent by 2028, with municipal and state surtaxes on top. VAT is 23 percent on the mainland. Figures are from a secondary source because tax authority pages could not be retrieved.
Key facts
Budget for IRC at 19 percent (15 percent on the first EUR 50,000 for SMEs) plus municipal surtax of up to 1.5 percent and state surtax on profits above EUR 1.5 million.
The rate is legislated to fall to 18 percent in 2027 and 17 percent in 2028.
Standard VAT is 23 percent on the mainland, lower in Madeira and the Azores.
Outbound dividends, interest and royalties bear 25 percent withholding (35 percent for blacklisted jurisdictions) unless a treaty or EU exemption applies.
Large groups fall under the Pillar Two regime enacted by Law 41/2024.
Who handles this in PortugalTax and structuringAccounting and annual filings · Hugo Ribeiro
Questions on this topic
6 statements on tax, accounting and reporting in Portugal
The 2026 minimum wage is EUR 920 a month. Contracts are permanent by default and dismissal requires cause, so termination planning matters. Employer social security is 23.75 percent.
Key facts
Pay at least EUR 920 a month from 1 January 2026.
Budget employer social security at 23.75 percent; employees pay 11 percent.
Use fixed-term contracts only where justified; open-ended contracts are the default and dismissal needs cause.
Non-EU employees typically come in on D1 or D3 visas.
Who handles this in PortugalEmployment, payroll and immigration
Questions on this topic
4 statements on employment, payroll and mobility in Portugal
Foreign investors may own real estate without restriction, and property rights must be registered within two months. Specific activities may need their own registration, and the SIFIDE II R&D incentive has been extended through 2026.
Key facts
Foreign buyers can acquire real estate freely but usually need a Portuguese tax number first.
Register property rights with the Land Registry within two months.
Check sector-specific registration before starting regulated activities.
SIFIDE II R&D tax relief is available through 2026.
Who handles this in PortugalLicences, permits and regulators
Questions on this topic
3 statements on licensing, incentives and sector rules in Portugal
Profits and dividends can be sent abroad without limits. Foreign shareholders need a Portuguese tax number, and non-EU/EEA residents must appoint a representative or use electronic notifications.
Key facts
Repatriation of profits and dividends is not limited.
Obtain a NIF for each foreign shareholder before formation and account opening.
Screen payments against EU sanctions, which national authorities enforce.
Who handles this in PortugalBanking and capitalPayments and currency
Questions on this topic
3 statements on banking, payments and capital movement in Portugal
Portugal applies EU customs law. Importers need an EORI number, and exports of listed dual-use items need authorisation.
Key facts
Customs law is the EU Union Customs Code.
Obtain an EORI number from the Portuguese customs authority before the first customs operation.
Check Annex I to the EU Dual-Use Regulation before exporting.
Who handles this in PortugalCustoms, trade and export controls
Questions on this topic
3 statements on customs, trade and supply chain in Portugal
The GDPR applies with Act 58/2019 as the national law. According to the European Commission's page, Portugal had not fully notified NIS2 transposition, and CNCS is the national cybersecurity authority. PDF invoices were expected to remain accepted to the end of 2026.
Key facts
Apply the GDPR and Act 58/2019 to all processing in Portugal.
Transfers outside the EU are simplest to adequacy countries.
Monitor NIS2 transposition; CNCS and CERT.PT are the national contacts.
PDF invoices were expected to remain accepted only until 31 December 2026; plan invoicing systems accordingly.
Who handles this in PortugalData protection and cyber
Questions on this topic
6 statements on data protection, cyber and digital compliance in Portugal
INPI is the national office for trademarks and designs. Portugal is part of the PCT and Madrid systems, so international filings can extend to Portugal.
Key facts
File national trademarks and designs with INPI; trademarks last 10 years and renew indefinitely.
Designs last five years, renewable up to 25 years.
Portugal can be designated through the PCT (since 1992) and the Madrid Protocol (since 1997).
Who handles this in PortugalTrade marks, patents and brands
Questions on this topic
4 statements on intellectual property in Portugal
Mergers meeting market-share or turnover tests must be notified to the Competition Authority. Acquisitions of strategic assets by non-EU/EEA investors can be reviewed under Decree-Law 138/2014. These points come from a 2025 law firm guide.
Key facts
Notify the AdC where a deal creates or reinforces a 50 percent share, or 30 to 50 percent with two parties above EUR 5 million turnover.
Notify also where aggregate Portuguese turnover exceeded EUR 100 million and two parties each exceed EUR 5 million.
Non-EU/EEA acquisitions of strategic assets may face government review.
EU rules on FDI screening are being revised.
Who handles this in PortugalBuying, selling and investing
Questions on this topic
4 statements on deals, merger control and restructuring in Portugal
AML due diligence obligations are set by Law 83/2017, and GDPR fines can reach 4 percent of worldwide turnover. Anti-corruption and whistleblowing rules could not be confirmed run.
Key facts
AML identification and due diligence rules come from Law 83/2017.
Data protection breaches can cost up to 4 percent of worldwide turnover.
Beneficial owners must be declared in the RCBE.
EU sanctions apply and are enforced nationally.
Who handles this in PortugalAnti-bribery, sanctions and compliance
Questions on this topic
2 statements on compliance, integrity and governance in Portugal
Portugal is a New York Convention state with a reciprocity reservation and recognises EU judgments without special procedure. Arbitration is governed by Law 63/2011, and mediation is voluntary.
Key facts
Foreign arbitral awards from other Convention states are enforced under the New York Convention, in force since 1995.
EU member state judgments are recognised and enforceable without a declaration of enforceability.
Arbitration follows Law 63/2011, and tribunals must issue a final award within a year of constitution.
Mediation under Law 29/2013 is voluntary.
Who handles this in PortugalDisputes and arbitration
Questions on this topic
5 statements on disputes and enforcement in Portugal
Sources last checked on 19 October 2026. None of it has been professionally reviewed yet: it is research checked against official and secondary sources by WONE Global, not legal or tax advice.
WONE Global Intelligence
Ask in your own words. Answers come from WONE Global's checked records, with every source shown, and end with the named Partner who can act. Go deeper on any point, or build a decision file.
WONE Global Partners
1 of 18 services have a WONE Global Partner in Portugal. For the other 17, WONE Global confirms whether a vetted Associate firm can act and tells you who it is before any work starts.
WONE Global Partners
Senior professionals responsible for WONE Global work in Portugal, under their own professional rules.
Lisbon · PortugalWONE Global Capability Partner · Portugal
What changed recently
From the Newsroom: changes recorded in this guide, each checked against its official source, with the date it takes effect.
Took effect 1 January 2026
Took effect 1 January 2026
Took effect 1 January 2026
Situations
Common problems that need someone on the ground, and worked scenarios involving Portugal.
Worked scenarios
Scenarios are representative of the work WONE Global coordinates, not specific client matters.
Save your questions, decisions and WONE activity in one account.
Forgot your password? Reset it securely.
Partner workspaces are for Partner firms. Explore partnership →
