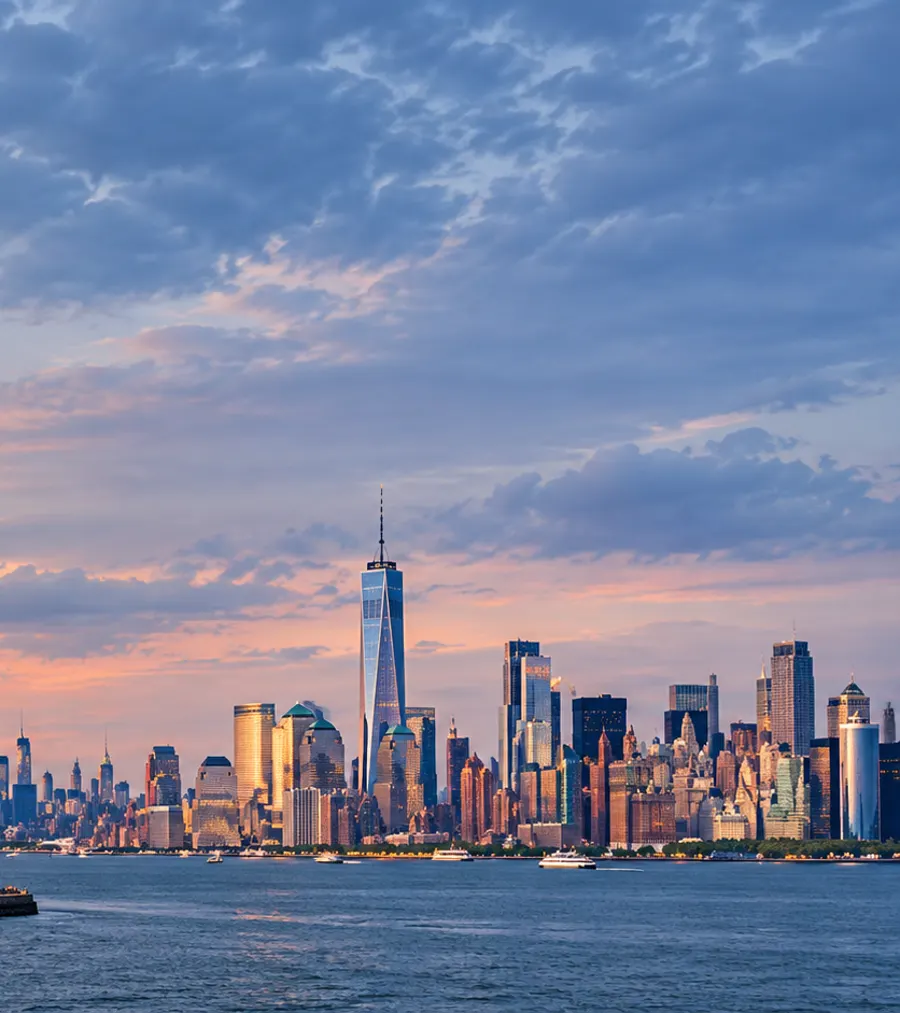


 São Paulo · Brazil
WONE Global Capability Partner · Brazil
Sourced guides to doing business in each market, and the status of every service there. Partners are in place in 32 markets so far.
One WONE Global Partner for each service in each market. Start from what you need to do, or go straight to a service.
Licences, value chains and the questions businesses in each industry ask first, with the services that usually apply.
Ask WONE Global what applies to your industry in a market, with the sources shown.
What one country changes for the other, worked journeys step by step, and who handles each side.
Named senior professionals, each admitted as the one firm for a service in their country, and the firms they lead.
One Partner per service, per jurisdiction, admitted by review against published criteria.
Every statement is labelled: source-checked, professionally reviewed or not yet checked, with its source and date where checked.
Answers come from statements checked against official sources, with the sources shown. Research, not advice.
Accomplished regional specialists and international cross-border intelligence, across 100 countries, with one contact and one published Standard.
Latin America · WONE Global market
Latin America’s largest economy with substantial tax, regulatory, investment and operating complexity. 1 of 18 services have a WONE Global Partner here. For the others, WONE Global confirms availability on request.
São Paulo · Thursday 22 October
23:13
Local time
Market guide · Source-checked research
Brazil is a federal republic where company, tax, labour and foreign exchange law is mainly federal, while states and municipalities levy their own consumption taxes. Foreign investors usually operate through a local company or an authorised branch, and foreign capital enjoys equal treatment but is monitored by the Central Bank. Profits face IRPJ and CSLL, dividends paid abroad carry 10% withholding from 2026, and the consumption tax system is being replaced by CBS and IBS in stages from 2026 to 2033.
Essentials guide · Source-checked research100% of statements checked against a source51 checked against an official source0 checked against a secondary sourceChecked 2026-10-19Not yet professionally reviewed
Brazil has a codified civil-law system. Key authorities for an incoming business are the Receita Federal (federal tax and customs), the state Juntas Comerciais and DREI (company registration and foreign branch authorisation), the Central Bank (foreign exchange and foreign capital), CADE (competition), the ANPD (data protection) and INPI (industrial property). The 2023 constitutional consumption tax reform (EC 132/2023, LC 214/2025) is the largest structural change under way and affects pricing, invoicing and systems for every business.
Key facts
Foreign investors usually operate through a Brazilian company registered with a state commercial registry, or through a branch, which needs prior federal authorisation. Registration runs through the national Redesim system and the company receives a CNPJ tax number. Foreign capital is monitored by the Central Bank.
Key facts
A branch of a foreign company needs prior authorisation, issued by DREI, before it can register with a Junta Comercial.
The branch must have a representative domiciled and resident in Brazil with powers to accept service, and capital allocated in reais.
Taking shares in a Brazilian company does not need branch authorisation; it is handled directly by the Junta Comercial.
Company opening follows three stages in Redesim: viability, registration including the CNPJ, and licensing, so municipal and state licences sit inside the process.
Foreign capital in Brazil is subject to Central Bank regulation and reporting, which should be planned alongside incorporation.
Who handles this in BrazilSetting up and running a companyLicences, permits and regulatorsBanking and capital
Questions on this topic
6 statements on entry, investment and company formation in Brazil
Profits are taxed by IRPJ at 15% plus a 10% surcharge and by CSLL at 9% for most companies. From 2026 dividends paid abroad carry 10% withholding, and Brazil applies a Pillar Two domestic minimum tax. The consumption tax system is being replaced by CBS and IBS between 2026 and 2033.
Key facts
IRPJ is 15% with a 10% surcharge on profit above BRL 20,000 a month; CSLL is 9% for most companies and 15% for financial and insurance entities.
Dividends paid abroad are subject to 10% withholding from 1 January 2026, with a carve-out for 2025 and earlier profits approved for distribution by 31 December 2025.
Large multinational groups (EUR 750 million revenue) pay the Adicional da CSLL to bring their Brazilian effective rate up to 15% from 2025.
2026 is the CBS and IBS test year; PIS and Cofins end in 2027, when the Selective Tax starts and IPI drops to zero for most goods.
ICMS and ISS are phased out between 2029 and 2032 and abolished in 2033, so invoicing, pricing and systems will change several times.
Who handles this in BrazilTax and structuringAccounting and annual filings
Questions on this topic
6 statements on tax, accounting and reporting in Brazil
Employment is heavily regulated by the CLT and the Constitution, with a national minimum wage set by decree each year. Employer payroll costs are significant: 20% social security plus accident-risk and third-party contributions. Foreign staff need a work visa or residence authorisation under the Migration Law.
Key facts
The national minimum wage is BRL 1,621 a month from 1 January 2026.
Employers pay 20% social security on total monthly remuneration.
On top, employers pay RAT at 1% to 3% by risk grade and third-party contributions that vary by activity.
Foreign employees need a temporary work visa or residence authorisation for work, usually backed by a job offer from a Brazilian entity.
Who handles this in BrazilEmployment, payroll and immigration
Questions on this topic
4 statements on employment, payroll and mobility in Brazil
Brazilian law gives foreign capital the same treatment as national capital, but sector laws restrict foreign participation in some fields. The Manaus Free Trade Zone keeps a tax advantage under the reform. Public bodies may agree to arbitration over disposable property rights.
Key facts
Foreign capital is entitled to the same legal treatment as national capital, subject to sector-specific rules.
The Manaus Free Trade Zone remains protected under the reform, with IPI kept only for that purpose from 2027.
Government and state-owned counterparties may use arbitration, which matters for concession and infrastructure contracts.
Who handles this in BrazilLicences, permits and regulators
Questions on this topic
3 statements on licensing, incentives and property in Brazil
Brazil has no general exchange controls on amounts, but all foreign exchange must pass through authorised institutions under the 2021 foreign exchange law. Remitting profits abroad requires proof that income tax was paid. Foreign capital is reported to the Central Bank.
Key facts
Foreign exchange operations are allowed without value limits, through institutions authorised by the Central Bank.
Profit and dividend remittances depend on proof of payment of the income tax due, so withholding must be settled first.
The current framework is Lei 14.286/2021, in force one year after publication on 30 December 2021.
The Central Bank regulates and monitors foreign capital stocks and flows.
Who handles this in BrazilPayments and currencyBanking and capital
Questions on this topic
4 statements on banking, foreign exchange and repatriation in Brazil
Brazil applies the Mercosur Common External Tariff and requires importers to register with the Receita Federal to use Siscomex. Import duty is charged on the customs value. New trade agreements, including Mercosur-EFTA, are starting to apply.
Key facts
Imports from outside Mercosur pay the Common External Tariff, classified under the NCM.
Importers and exporters must be registered (habilitação) with the Receita Federal before operating in Siscomex.
Mercosur-EFTA quotas apply from 1 October 2026 for Iceland and 1 November 2026 for Norway.
Who handles this in BrazilCustoms, trade and export controls
Questions on this topic
4 statements on trade, customs and supply chain in Brazil
The LGPD applies to processing in Brazil and to foreign businesses targeting people in Brazil. It restricts international transfers to listed mechanisms, requires a data protection officer and incident notification, and allows fines of up to 2% of revenue. The ANPD was restructured as an autonomous agency in February 2026.
Key facts
The LGPD reaches foreign controllers that offer goods or services to, or monitor, people in Brazil.
Cross-border transfers need a listed basis such as standard contractual clauses or global corporate rules.
Controllers must appoint an encarregado and notify the ANPD and data subjects of risky security incidents.
Fines reach 2% of Brazilian revenue, capped at BRL 50 million per infringement.
The ANPD is now an autonomous agency under Lei 15.352/2026 and also enforces the children's online protection law.
Who handles this in BrazilData protection and cyber
Questions on this topic
6 statements on data, privacy and technology in Brazil
Trademarks and patents are handled by INPI. Brazil is in both the Madrid system and the PCT, so international filings can designate Brazil. Trademark registrations are renewable every ten years.
Key facts
International trademark applications can designate Brazil under the Madrid Protocol since October 2019.
PCT applications can enter the Brazilian national phase; Brazil has been a PCT state since 1978.
INPI registers trademarks, renewable every ten years.
Invention patents last 20 years and utility models 15 years.
Who handles this in BrazilTrade marks, patents and brands
Questions on this topic
4 statements on intellectual property in Brazil
Deals above turnover thresholds must be cleared by CADE before closing. Early completion is penalised with fines and nullity. CADE's review period is capped at 240 days, extendable by 90.
Key facts
Notification is mandatory when one group has BRL 750 million and another BRL 75 million of Brazilian revenue.
Review is suspensive: do not close before clearance.
Gun jumping can void the acts and bring fines from BRL 60,000 to BRL 60 million.
The statutory review period is 240 days, extendable once by 90 days.
Who handles this in BrazilBuying, selling and investing
Questions on this topic
4 statements on transactions, competition and restructuring in Brazil
The Clean Company Act imposes strict corporate liability for bribery and other acts against public administration, including by foreign companies present in Brazil. Fines run up to 20% of gross revenue. Integrity programmes reduce sanctions.
Key facts
Companies are strictly liable for corrupt acts done in their interest, including foreign companies with a presence in Brazil.
Fines range from 0.1% to 20% of prior-year gross revenue.
An effective integrity programme with whistle-blowing channels is taken into account in sanctions.
The CGU negotiates leniency agreements at federal level; the law also reaches bribery of foreign officials by Brazilian companies.
Who handles this in BrazilAnti-bribery, sanctions and compliance
Questions on this topic
5 statements on compliance, anti-corruption and risk in Brazil
Brazil has a modern arbitration law and is party to the New York Convention. Foreign arbitral awards and foreign judgments are recognised through homologation by the Superior Court of Justice. Domestic awards are final and enforceable like judgments.
Key facts
Brazil applies the New York Convention without reservations.
Foreign arbitral awards need only STJ homologation.
Domestic awards are final, not subject to appeal, and enforceable as judgments.
Foreign court judgments are enforced through a letter rogatory or a homologation action.
Who handles this in BrazilDisputes and arbitration
Questions on this topic
5 statements on disputes and enforcement in Brazil
Sources last checked on 19 October 2026. None of it has been professionally reviewed yet: it is research checked against official and secondary sources by WONE Global, not legal or tax advice.
WONE Global Intelligence
Ask in your own words. Answers come from WONE Global's checked records, with every source shown, and end with the named Partner who can act. Go deeper on any point, or build a decision file.
WONE Global Partners
1 of 18 services have a WONE Global Partner in Brazil. For the other 17, WONE Global confirms whether a vetted Associate firm can act and tells you who it is before any work starts.
WONE Global Partners
Senior professionals responsible for WONE Global work in Brazil, under their own professional rules.
São Paulo · BrazilWONE Global Capability Partner · Brazil
Business corridors
Where business from Brazil most often goes — and where WONE Global is already on both sides.
What changed recently
From the Newsroom: changes recorded in this guide, each checked against its official source, with the date it takes effect.
Takes effect 1 January 2027
Took effect 1 October 2026
Took effect 25 February 2026
Took effect 1 January 2026
Save your questions, decisions and WONE activity in one account.
Forgot your password? Reset it securely.
Partner workspaces are for Partner firms. Explore partnership →