





 Edmonton · Canada

Submission received
Your information has been recorded by WONE.
Sourced guides to doing business in each market, and the status of every service there. Partners are in place in 32 markets so far.
One WONE Global Partner for each service in each market. Start from what you need to do, or go straight to a service.
Licences, value chains and the questions businesses in each industry ask first, with the services that usually apply.
Ask WONE Global what applies to your industry in a market, with the sources shown.
What one country changes for the other, worked journeys step by step, and who handles each side.
Named senior professionals, each admitted as the one firm for a service in their country, and the firms they lead.
One Partner per service, per jurisdiction, admitted by review against published criteria.
Every statement is labelled: source-checked, professionally reviewed or not yet checked, with its source and date where checked.
Answers come from statements checked against official sources, with the sources shown. Research, not advice.
Accomplished regional specialists and international cross-border intelligence, across 100 countries, with one contact and one published Standard.
North America · WONE Global market
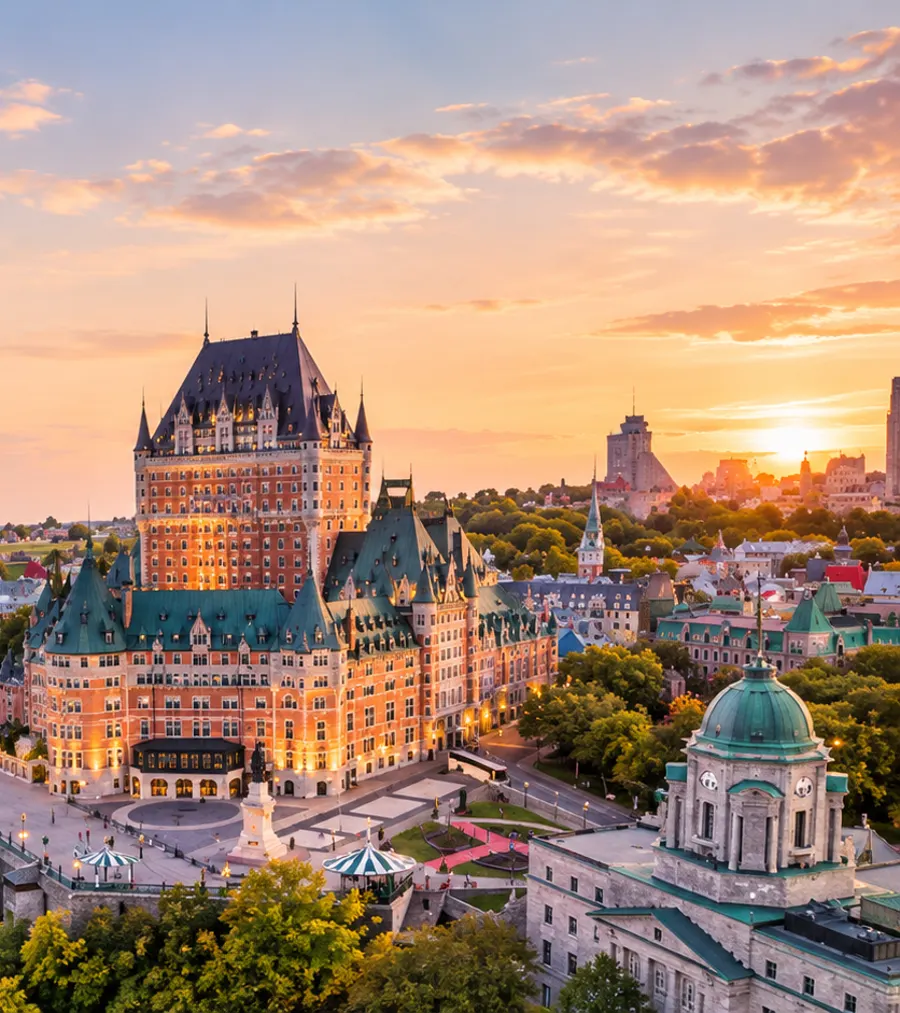
Canada is covered by WONE for cross-border business discovery, with links to relevant expertise, professionals, industries and market intelligence. 2 of 18 services have a WONE Global Partner here. For the others, WONE Global confirms availability on request.
Toronto · Thursday 22 October
22:14
Local time
Market guide · Source-checked research
Canada is a federation in which company, tax, employment and privacy rules are split between Ottawa and the ten provinces and three territories. Foreign investors usually incorporate federally or provincially; federal corporations need at least one director and ordinarily a quarter of resident Canadian directors, and every foreign acquisition or new business must be notified or reviewed under the Investment Canada Act. Federal corporate tax is 15 percent plus provincial tax (11.5 percent in Ontario), and GST of 5 percent or HST of 13 to 15 percent applies. Most employment rules, including minimum wage, are provincial except in federally regulated sectors.
Essentials guide · Source-checked research98% of statements checked against a source48 checked against an official source1 checked against a secondary sourceChecked 2026-10-19Not yet professionally reviewed
Canada has a common law system in every province except Quebec, which uses civil law for private matters. Federal bodies include Corporations Canada and ISED (incorporation, Investment Canada Act, CIPO), the Canada Revenue Agency, the Competition Bureau, the Office of the Privacy Commissioner, OSFI, FINTRAC, the Canada Border Services Agency and Global Affairs Canada (export controls and sanctions). Provinces run their own corporate registries, employment standards, securities regulators and courts, and Quebec and Alberta administer their own corporate income tax.
Key facts
Foreign investors can incorporate under the federal Canada Business Corporations Act or a provincial statute, or register an existing company extra-provincially. Every new Canadian business or acquisition by a non-Canadian must be notified under the Investment Canada Act, larger deals are reviewed for net benefit, and any investment can be reviewed for national security. Federal corporations must track and file their individuals with significant control.
Key facts
File an Investment Canada Act notification within 30 days after starting or acquiring a Canadian business; acquisitions above the 2026 thresholds (for example CAD 2.179 billion enterprise value for trade agreement investors) need approval first.
National security review can reach any foreign investment, including minority stakes, so sensitive-sector investors should consider a voluntary filing before closing.
A federal corporation needs at least one director and ordinarily 25 percent resident Canadian directors (at least one where the board has fewer than four), which shapes board design for foreign-owned subsidiaries.
Federal corporations must keep an individuals with significant control register (25 percent threshold) and file it with Corporations Canada with each annual return and within 15 days of changes.
Online federal incorporation costs CAD 200 and the online annual return CAD 12; provincial registration to carry on business in each province is a separate step.
Who handles this in CanadaSetting up and running a companyLicences, permits and regulatorsBuying, selling and investing
Questions on this topic
6 statements on entry, investment and company formation in Canada
Corporate income tax is levied federally at a net 15 percent and provincially on top, so the combined rate depends on the province. GST at 5 percent applies nationally, replaced by HST of 13 to 15 percent in the harmonised provinces. Payments to non-residents attract 25 percent withholding unless reduced by treaty.
Key facts
Combined corporate tax is the 15 percent federal rate plus the provincial rate, for example 11.5 percent in Ontario or 12 percent in British Columbia; Quebec and Alberta collect their own corporate tax.
Charge 5 percent GST, or HST at 13 percent in Ontario, 14 percent in Nova Scotia and 15 percent in New Brunswick, Newfoundland and Labrador and Prince Edward Island.
GST/HST registration is required once taxable supplies pass CAD 30,000 over four quarters, and non-residents carrying on business in Canada are caught even without a permanent establishment.
Withhold 25 percent Part XIII tax on taxable payments to non-residents unless a treaty in force reduces it, and file T2 returns within six months of year end, including for non-resident corporations doing business in Canada.
Who handles this in CanadaTax and structuringAccounting and annual filings
Questions on this topic
6 statements on tax, accounting and statutory reporting in Canada
Employment standards are provincial for most businesses and federal only for federally regulated sectors, so minimum wage, notice and leave depend on where and in what industry staff work. Employers deduct and match CPP (or QPP in Quebec) and EI contributions. Hiring foreign workers usually needs a Labour Market Impact Assessment.
Key facts
Minimum wage is CAD 18.15 per hour for federally regulated employers from 1 April 2026; in Ontario the general rate is CAD 17.95 from 1 October 2026.
Federally regulated employers must give 2 weeks' notice, rising to up to 8 weeks with service, plus severance after 12 months; provincial statutes and common law notice set different minimums elsewhere.
For 2026, CPP is 5.95 percent each for employee and employer up to CAD 74,600 of earnings, and EI is 1.63 percent for employees with employers paying 1.4 times that amount.
Most temporary foreign hires need a positive LMIA from ESDC unless an International Mobility Program exemption applies.
Who handles this in CanadaEmployment, payroll and immigrationContracts and commercial law
Questions on this topic
6 statements on employment, payroll and mobility in Canada
Licensing is spread across federal, provincial, territorial and municipal governments, with banks, telecoms, airlines and interprovincial transport under federal jurisdiction and most other activity provincial. Federal tenders are published on CanadaBuys, and the federal government says it is prioritising Canadian suppliers.
Key facts
Check permits at every level of government; the federal BizPaL service searches federal, provincial, territorial and municipal requirements together.
Banks, telecommunications, broadcasting, air transport, interprovincial transport and pipelines are federally regulated; other sectors are mainly licensed provincially.
Federal tenders are published on CanadaBuys, and Public Services and Procurement Canada states it is prioritising purchases from Canadian suppliers.
Who handles this in CanadaLicences, permits and regulators
Questions on this topic
4 statements on licensing, sector rules and real estate in Canada
Federally regulated banks and insurers are supervised by OSFI, and FINTRAC publishes the rules for reporting suspicious or large transactions. Deposits at CDIC members are insured up to CAD 100,000. We did not find an official statement on exchange controls, and business account onboarding requirements are set by individual banks.
Key facts
Banks, trust and loan companies and federally regulated insurers are supervised by OSFI, with conduct rules overseen by the Financial Consumer Agency of Canada.
Banks will ask for ownership and source-of-funds information at onboarding; FINTRAC publishes the reporting rules for suspicious and large transactions.
CDIC insures eligible deposits at member institutions up to CAD 100,000, which matters for treasury placement of operating cash.
Individuals opening personal accounts need two original identity documents, and foreign passports are accepted.
Who handles this in CanadaBanking and capitalPayments and currencyAnti-bribery, sanctions and compliance
Questions on this topic
4 statements on banking, payments and capital flows in Canada, 1 not yet checked against a source
Customs is federal and run by the Canada Border Services Agency, export controls and sanctions by Global Affairs Canada. In 2026 Canada applies counter-tariffs to a list of US products, which affects cost planning for US-sourced goods.
Key facts
Goods and technology on the Export Control List, and some other controlled goods, need an export permit from Global Affairs Canada.
Check the current counter-tariff list before importing US-origin goods; the list in force as of 8 September 2026 is published with CBSA guidance.
CBSA handles classification, duty and recourse, and importers can appoint a licensed customs broker.
Canada's sanctions legislation applies to trade with listed countries and persons, enforced by the RCMP and CBSA.
Who handles this in CanadaCustoms, trade and export controlsAnti-bribery, sanctions and compliance
Questions on this topic
4 statements on customs, trade and product rules in Canada
PIPEDA governs personal information handled in commercial activities, alongside provincial private-sector laws in some provinces. Breaches posing a real risk of significant harm must be reported to the Privacy Commissioner and to affected individuals. Transfers abroad are managed through accountability and contractual safeguards rather than a ban.
Key facts
PIPEDA applies to personal information collected, used or disclosed in commercial activities and to employee data of federal works, undertakings or businesses.
Report breaches that create a real risk of significant harm to the OPC and notify individuals as soon as feasible; keep a record of every breach for two years.
When personal information goes to a service provider, including one outside Canada, the organisation stays responsible and must secure comparable protection by contract.
Who handles this in CanadaData protection and cyberContracts and commercial law
Questions on this topic
4 statements on data protection, cyber security and e-invoicing in Canada
CIPO registers patents, trademarks and copyright at federal level. Patents run up to 20 years from filing on a first-to-file basis, trademarks are registered for 10-year renewable periods, and Canada participates in both the Madrid Protocol and the Patent Cooperation Treaty.
Key facts
File patents early: Canada is first-to-file, protection lasts up to 20 years from filing, and inventors have 12 months after their own disclosure to file.
Patent applications can enter through the PCT, and examination must be requested and maintenance fees paid to keep rights alive.
Trademark registrations last 10 years and are renewable; Canada can be designated in a Madrid international registration, or used as the office of origin.
Copyright generally lasts 70 years after the author's death.
Who handles this in CanadaTrade marks, patents and brands
Questions on this topic
5 statements on intellectual property and brand protection in Canada
Large mergers must be notified to the Competition Bureau and cannot close during a 30-day waiting period, while acquisitions of control by non-Canadians fall under the Investment Canada Act. Insolvent groups with over CAD 5 million of debt can restructure under the court-supervised CCAA.
Key facts
Mergers above the CAD 400 million size-of-parties and CAD 93 million size-of-transaction thresholds must be notified, and closing is barred during the 30-day waiting period unless waived.
Reviewable foreign acquisitions get a 45-day net benefit decision period, extendable by 30 days, and are deemed approved if the deadline passes without notice.
The CCAA, for insolvent corporations owing over CAD 5 million, provides a court-ordered stay and a court-appointed monitor; smaller businesses use the Bankruptcy and Insolvency Act.
Who handles this in CanadaBuying, selling and investingLicences, permits and regulatorsContracts and commercial law
Questions on this topic
4 statements on m&a, merger control, investment screening and insolvency in Canada
The Corruption of Foreign Public Officials Act criminalises foreign bribery and related books-and-records misconduct, reaches Canadian entities' conduct abroad and no longer exempts facilitation payments. Sanctions apply to persons in Canada and Canadians abroad, and extractive companies must report payments to governments.
Key facts
Foreign bribery and falsifying records to hide bribes each carry up to 14 years' imprisonment.
Canadian corporations and citizens can be prosecuted for bribery committed anywhere in the world, and facilitation payments have been prohibited since 2017.
Sanctions screening and asset-freeze reporting duties apply to everyone in Canada and to Canadians outside Canada.
Oil, gas and mining businesses within ESTMA must publish payments to governments in Canada and abroad.
Who handles this in CanadaAnti-bribery, sanctions and complianceContracts and commercial law
Questions on this topic
6 statements on anti-bribery, compliance and supply-chain duties in Canada
Canada is a party to the New York Convention, applying it to commercial relationships everywhere except Quebec, where no such limit applies. Courts, arbitration statutes and the enforcement of foreign judgments are largely provincial matters and could not yet be confirmed from official sources.
Key facts
Foreign arbitral awards from commercial relationships can be enforced under the New York Convention, to which Canada acceded in 1986.
Who handles this in CanadaDisputes and arbitrationContracts and commercial law
Questions on this topic
1 statement on courts, arbitration and enforcement in Canada
Sources last checked on 19 October 2026. None of it has been professionally reviewed yet: it is research checked against official and secondary sources by WONE Global, not legal or tax advice.
WONE Global Intelligence
Ask in your own words. Answers come from WONE Global's checked records, with every source shown, and end with the named Partner who can act. Go deeper on any point, or build a decision file.
WONE Global Partners
2 of 18 services have a WONE Global Partner in Canada. For the other 16, WONE Global confirms whether a vetted Associate firm can act and tells you who it is before any work starts.
WONE Global Partners
Senior professionals responsible for WONE Global work in Canada, under their own professional rules.
Edmonton · Canada Edmonton · Canada
 Edmonton · Canada
WONE Global Capability Partner · Canada
 Edmonton · Canada
WONE Global Capability Partner · Canada
As the Managing Partner at Faber LLP, my focus on corporate tax strategy has solidified our reputation for delivering tailored solutions. With an extensive background in tax law and a CPA designation, I lead our team in…
What changed recently
From the Newsroom: changes recorded in this guide, each checked against its official source, with the date it takes effect.
Took effect 1 October 2026
Took effect 10 September 2026
Took effect 8 September 2026
Took effect 1 April 2026
Save your questions, decisions and WONE activity in one account.
Forgot your password? Reset it securely.
Partner workspaces are for Partner firms. Explore partnership →