
People & firms

The WONE Global Partners in each market.

Named senior professionals, each admitted as the one firm for a service in their country, and the firms they lead.

For professional firms

Lead your service in your market.

One Partner per service, per jurisdiction, admitted by review against published criteria.

Open Partnerships→
Insights

Sourced answers on doing business across borders.

Every statement is labelled: source-checked, professionally reviewed or not yet checked, with its source and date where checked.

Ask WONE Global

Ask your question.

Answers cite WONE Global's sourced statements and show how each one was checked. Research, not advice.

Ask WONE Global→

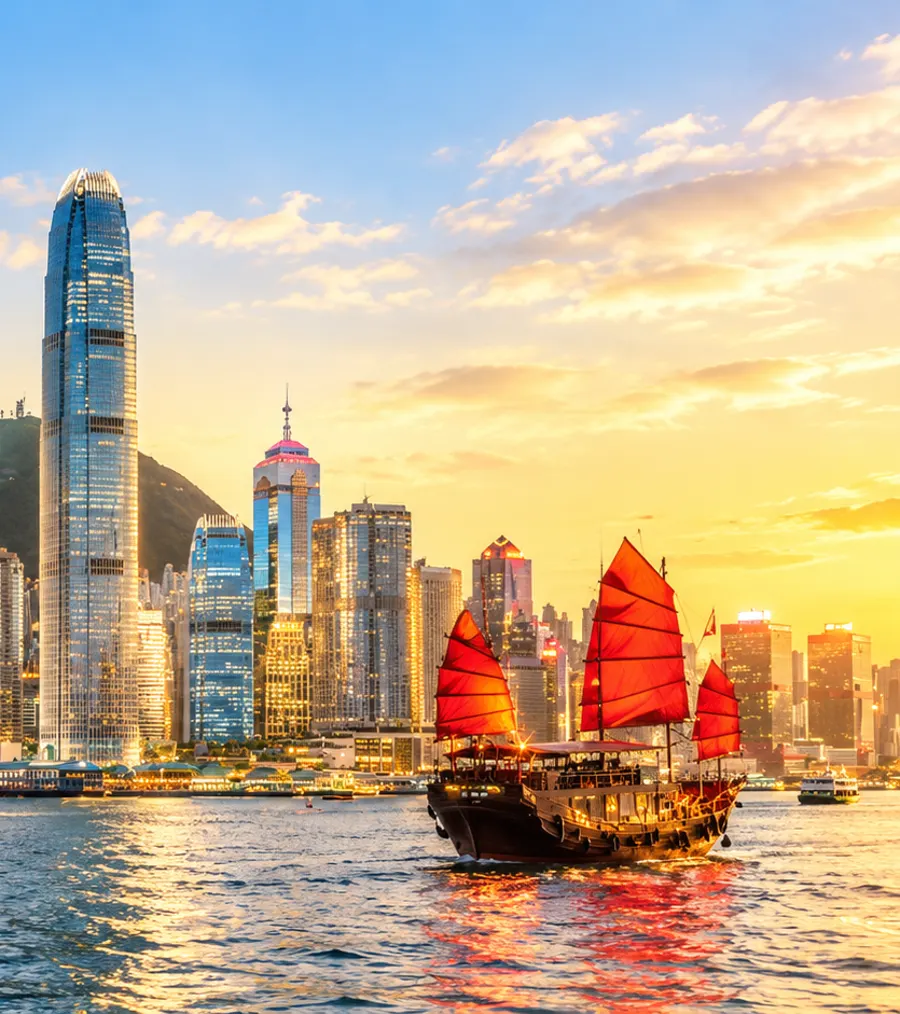
Hong Kong × Tax & International Structuring

Tax & International Structuring in Hong Kong

Tax and structuring for businesses, investments and deals that cross borders. In Hong Kong, that means local law, local regulators and local practice, handled by a qualified professional who practises there.

Who handles this workNamed WONE Global lead
  1. What happens next · 1WONE Global acknowledges your requirement and confirms what's involved.
  2. 2The local firm runs its conflict checks.
  3. 3We confirm Yvonne Chow as your named lead.
  4. 4You agree scope and fees directly with the firm before work begins.
Hong Kong at a glanceEast Asia

Hong Kong · Wednesday 4 November

04:40

Local time

Currency
HKD
Working week
Monday – Friday
Dialling code
+852
Region
East Asia
Doing business in Hong Kong →

What the rules say in Hong Kong

Tax & International Structuring, the essentials

From the Hong Kong market guide: the points that matter most for tax & international structuring, each with the source it was checked against.

Essentials guide · Source-checked research88% of statements checked against a source43 checked against an official source0 checked against a secondary sourceChecked 2026-10-196 held back until checked against an official source1 topic includes AI-written statements, not source-checkedNot yet professionally reviewed

  • Corporations pay profits tax at 8.25% on the first HK$2,000,000 of assessable profits and 16.5% on the remainder.

    Two-tiered rates from year of assessment 2018/19; unincorporated businesses pay 7.5% and 15%.Inland Revenue Department, HKSAR Government · checked 2026-10-19
  • Profits tax is charged only on profits arising in or derived from Hong Kong, and no tax is levied on profits arising abroad even if they are remitted to Hong Kong.

    Source rules are fact-specific; the foreign-sourced income exemption regime applies to certain passive income received by multinational group entities.Inland Revenue Department, HKSAR Government · checked 2026-10-19
  • Hong Kong has no sales tax or VAT and no withholding tax on dividends and interest.

    Royalties paid to non-residents are treated differently (see hk-tax-004).Invest Hong Kong (InvestHK), HKSAR Government · checked 2026-10-19
  • Sums received by a non-resident for the use of patents, trade marks, copyright material and similar rights in Hong Kong are deemed Hong Kong-sourced, and the payer must deduct the tax when making the payment.

    Royalties and similar payments to non-residents; the effective rate depends on the recipient's circumstances and was not stated on the page.Inland Revenue Department, HKSAR Government · checked 2026-10-19
  • Hong Kong applies a 15% global minimum tax through an income inclusion rule and the Hong Kong minimum top-up tax for fiscal years beginning on or after 1 January 2025; the undertaxed profits rule is not yet in effect.

    Multinational groups with annual consolidated revenue of EUR 750 million or more in at least two of the four preceding fiscal years. Enacted by the Inland Revenue (Amendment) (Minimum Tax for Multinational Enterprise Groups) Ordinance 2025 on 6 June 2025. Top-up tax notification is due within six months after the fiscal year end.Inland Revenue Department, HKSAR Government · checked 2026-10-19
  • An entity is exempt from preparing transfer pricing master and local files if it meets any two of: revenue not over HK$400 million, total assets not over HK$300 million, and not more than 100 employees; otherwise the files are due within 9 months after the accounting period ends.

    Separate related-party transaction thresholds exempt specific categories from the local file; IRO section 58C.Inland Revenue Department, HKSAR Government · checked 2026-10-19

Read the full guide: Tax, accounting and reporting

Scope

What the service covers here

  1. 01Review the proposed cross-border structure
  2. 02Identify direct and indirect tax exposures
  3. 03Consider withholding, treaty and transfer-pricing issues
  4. 04Coordinate implementation across the relevant jurisdictions

Key questions

What we will work through with you

  • What needs to be decided before tax & international structuring work starts?
  • Who is professionally responsible in each country?
  • Which other work, such as tax or employment, must happen at the same time?
  • What information and decisions are needed from the business?

If your work involves another country or another area of expertise, WONE Global brings in the right professional and keeps all advisers informed.

WONE Global Partners in Hong Kong

Other WONE Global Partners here

The other named professionals responsible for WONE Global work in Hong Kong.

WONE Global Intelligence

Ask about tax & international structuring in Hong Kong

Ask in your own words. Answers come from WONE Global's checked records, with every source shown, and end with the named Partner who can act. Go deeper on any point, or build a decision file.

Contact WONE Global

Discuss Tax & International Structuring in Hong Kong.
