



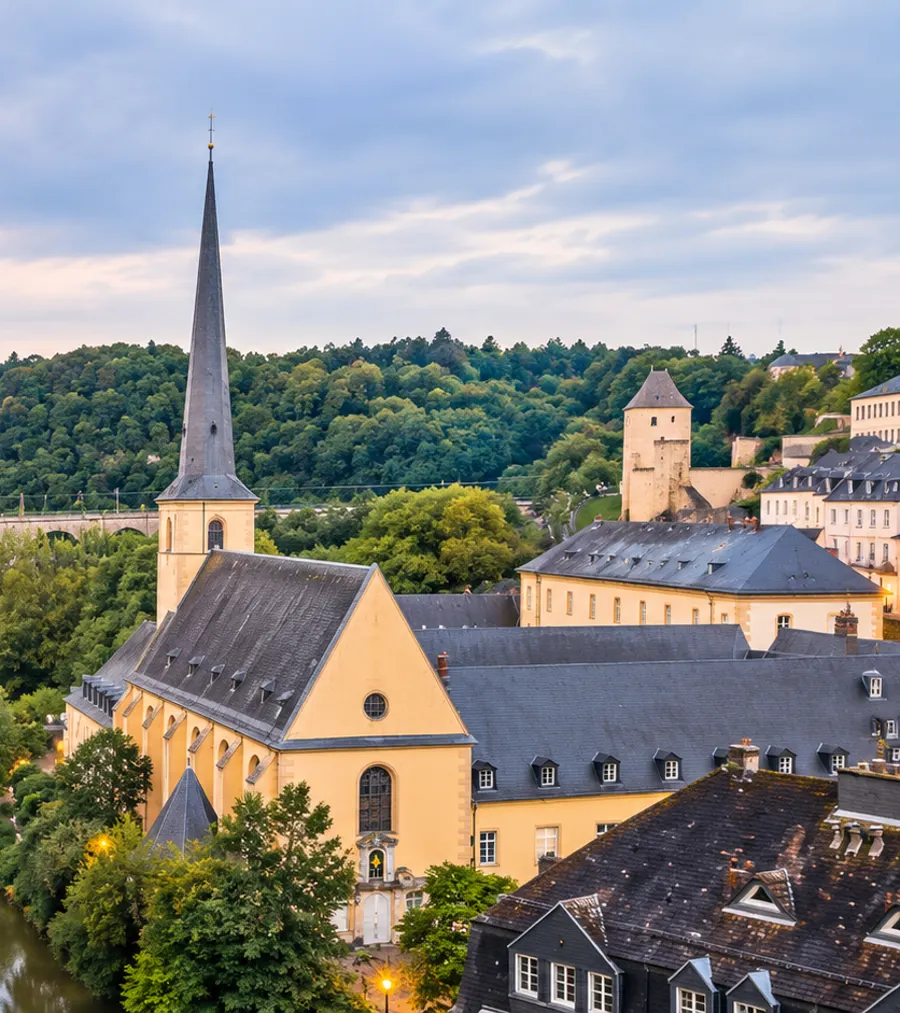
 Luxembourg · Luxembourg
WONE Global Partner · Luxembourg
Sourced guides to doing business in each market, and the status of every service there. Partners are in place in 34 markets so far.
One WONE Global Partner for each service in each market. Start from what you need to do, or go straight to a service.
Describe what you need. WONE Global names the service and the professional before any work begins.
Bring a requirement →Licences, value chains and the questions businesses in each industry ask first, with the services that usually apply.
What one country changes for the other, worked journeys step by step, and who handles each side.
When cross-border business becomes a dispute, UNIONE™, also part of the UNBOUNDED™ Global Ecosystem, prevents it, resolves it, arbitrates it and plans enforcement. 334 Fellows in 58 countries.
41 jurisdictions, each with primary sources and the date last checked.
Named senior professionals, each admitted as the one firm for a service in their country, and the firms they lead.
One Partner per service, per jurisdiction, admitted by review against published criteria.
Every statement is labelled: source-checked, professionally reviewed or not yet checked, with its source and date where checked.
Answers cite WONE Global's sourced statements and show how each one was checked. Research, not advice.
Accomplished regional specialists and international cross-border intelligence, across 100 countries, with one contact and one published Standard.
Luxembourg × Tax & International Structuring
Tax and structuring for businesses, investments and deals that cross borders. In Luxembourg, that means local law, local regulators and local practice, handled by a qualified professional who practises there.
On request
No WONE Global Partner holds this yet. Send us your requirement: WONE Global confirms whether a vetted Associate firm can act, tells you who it is and checks for conflicts before any work begins.
Bring a requirement →Luxembourg City · Thursday 5 November
09:30
Local time
What the rules say in Luxembourg
From the Luxembourg market guide: the points that matter most for tax & international structuring, each with the source it was checked against.
Essentials guide · Source-checked research97% of statements checked against a source29 checked against an official source8 checked against a secondary sourceChecked 2026-10-19Not yet professionally reviewed
From tax year 2025, corporate income tax is 16% on taxable income above EUR 200,000 and 14% on income below EUR 175,000.
Between EUR 175,000 and EUR 200,000: EUR 24,500 plus 30% of the excess over EUR 175,000. A 7% solidarity surtax and municipal business tax are added.PwC Worldwide Tax Summaries · checked 2026-10-19Companies pay annual net wealth tax of 0.5% on net assets up to EUR 500 million and EUR 2.5 million plus 0.05% on the excess, with a minimum net wealth tax of EUR 535 to EUR 4,815 from tax year 2025 depending on balance sheet total.
PwC Worldwide Tax Summaries · checked 2026-10-19The combined rate of corporate income tax, 7% solidarity surtax and 6.75% municipal business tax for a company in Luxembourg City is 23.87%.
Tax year 2025; municipal business tax rates vary by commune.PwC Worldwide Tax Summaries · checked 2026-10-19The standard Luxembourg VAT rate is 17%, with an intermediate rate of 14%, a reduced rate of 8% and a super-reduced rate of 3%.
Examples: 3% for most food and books; 8% for gas and electricity; 14% for certain wines and securities safekeeping.PwC Worldwide Tax Summaries · checked 2026-10-19Dividends carry 15% withholding tax, while interest and royalties paid to non-residents are generally not subject to withholding tax.
0% on dividends to qualifying corporate shareholders, generally holding at least 10% or shares acquired for at least EUR 1.2 million for 12 months, subject to anti-abuse rules. Profit-participating interest may be treated as a dividend.PwC Worldwide Tax Summaries · checked 2026-10-19Luxembourg's Pillar Two minimum tax law was enacted on 22 December 2023; the undertaxed profits rule applies to fiscal years beginning on or after 31 December 2024 and the first GloBE Information Return for calendar-year groups is due by 30 June 2026.
In-scope multinational and large domestic groups.PwC Worldwide Tax Summaries · checked 2026-10-19Sales of Luxembourg real estate attract registration duty of 7%, plus a 3% surtax in Luxembourg City.
Contributions in exchange for shares: 3.2% plus 0.3% in Luxembourg City.PwC Worldwide Tax Summaries · checked 2026-10-19Read the full guide: Tax, accounting and statutory reporting
Scope
Key questions
If your work involves another country or another area of expertise, WONE Global brings in the right professional and keeps all advisers informed.
WONE Global Partners in Luxembourg
No named lead for Tax & International Structuring yet — these WONE Global professionals already work in Luxembourg and can bring the right local colleague in.
Also in Luxembourg
Appointed services show their named professional. Open positions link directly to the Expression of Interest form.
Cases
The cases this service leads or joins, each with what is at stake, how WONE Global handles it and who handles it in Luxembourg.
WONE Global Intelligence
Ask in your own words. Answers come from WONE Global's checked records, with every source shown, and end with the named Partner who can act. Go deeper on any point, or build a decision file.
Contact WONE Global
Save your questions, decisions and WONE activity in one account.
Forgot your password? Reset it securely.
Partner workspaces are for Partner firms. Explore partnership →
