



Submission received
Your information has been recorded by WONE.
Sourced guides to doing business in each market, and the status of every service there. Partners are in place in 38 markets so far.
One WONE Global Partner for each service in each market. Start from what you need to do, or go straight to a service.
Describe what you need. WONE Global names the service and the professional before any work begins.
Bring a requirement →Licences, value chains and the questions businesses in each industry ask first, with the services that usually apply.
What one country changes for the other, worked journeys step by step, and who handles each side.
When cross-border business becomes a dispute, UNIONE™, also part of the UNBOUNDED™ Global Ecosystem, prevents it, resolves it, arbitrates it and plans enforcement. 334 Fellows in 58 countries.
41 jurisdictions, each with primary sources and the date last checked.
Named senior professionals, each admitted as the one firm for a service in their country, and the firms they lead.
One Partner per service, per jurisdiction, admitted by review against published criteria.
Every statement is labelled: source-checked, professionally reviewed or not yet checked, with its source and date where checked.
Answers cite WONE Global's sourced statements and show how each one was checked. Research, not advice.
Accomplished regional specialists and international cross-border intelligence, across 100 countries, with one contact and one published Standard.
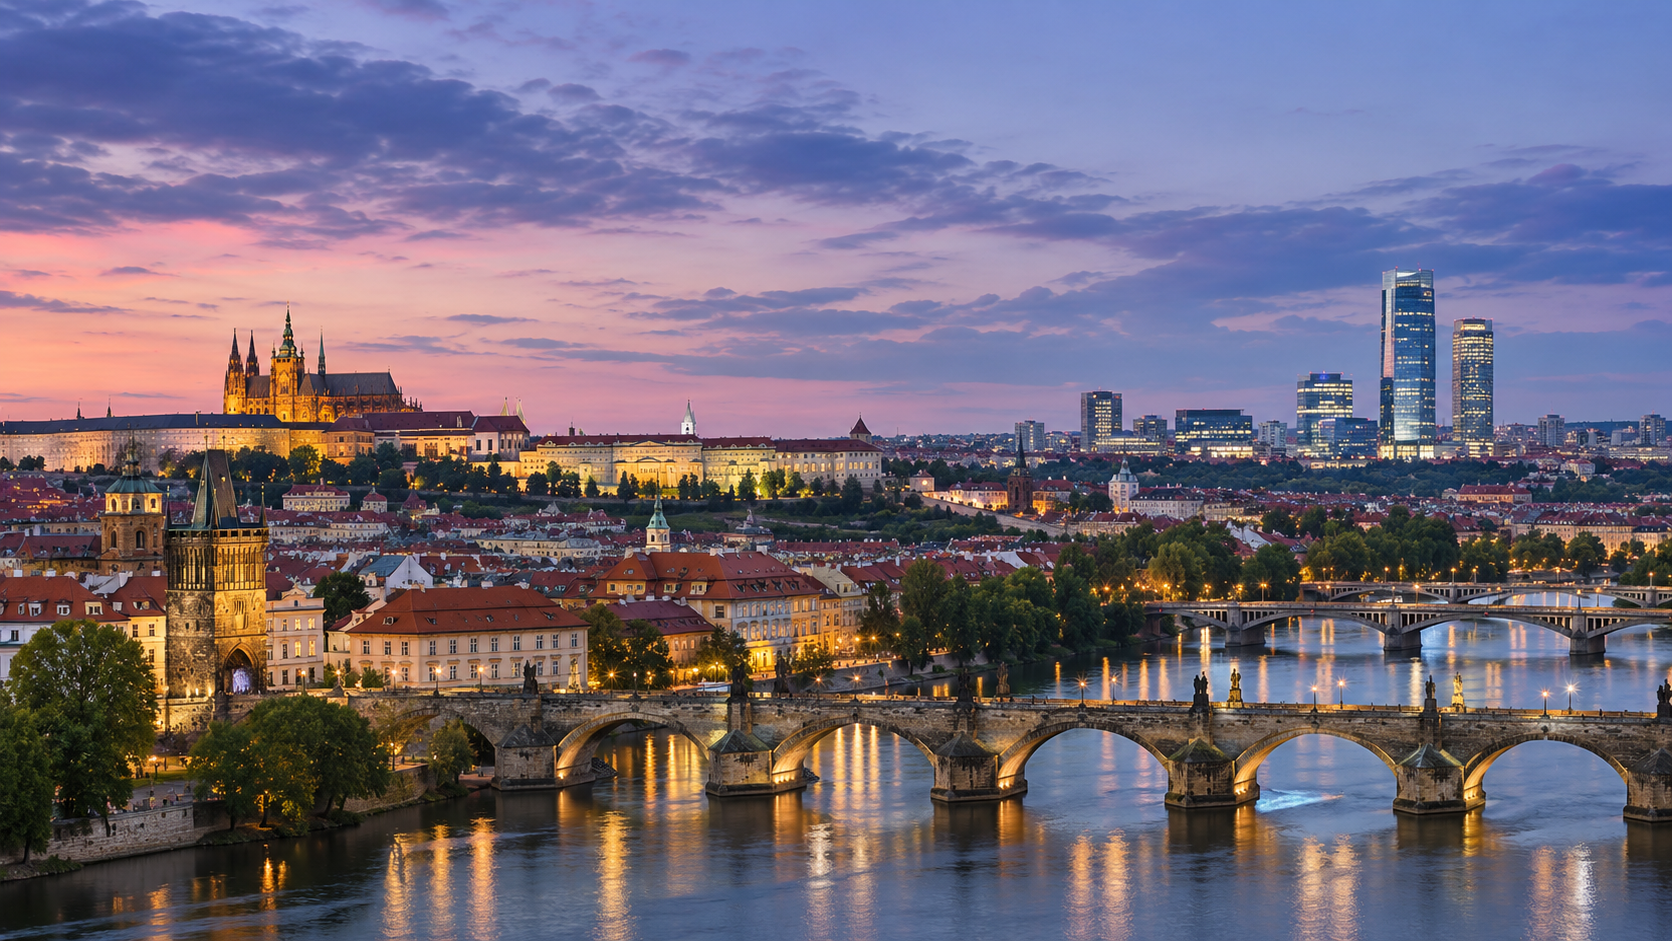
Czech Republic × Tax & International Structuring
Tax and structuring for businesses, investments and deals that cross borders. In the Czech Republic, that means local law, local regulators and local practice, handled by a qualified professional who practises there.
On request
No WONE Global Partner holds this yet. Send us your requirement: WONE Global confirms whether a vetted Associate firm can act, tells you who it is and checks for conflicts before any work begins.
Bring a requirement →Prague · Sunday 22 November
18:06
Local time
What the rules say in the Czech Republic
From the Czech Republic market guide: the points that matter most for tax & international structuring, each with the source it was checked against.
Essentials guide · Source-checked research100% of statements checked against a source24 checked against an official source13 checked against a secondary sourceChecked 2026-10-19Not yet professionally reviewed
The corporate income tax rate is 21% for tax periods starting in 2024, up from 19% previously.
Corporate taxpayers; special rates apply to certain funds.PwC Worldwide Tax Summaries · checked 2026-10-19Withholding tax on dividends, interest and royalties paid to non-residents is generally 15%, rising to 35% for recipients in non-EU and non-EEA countries without an enforceable tax treaty or tax information exchange agreement.
Domestic rates before treaty or EU directive relief.PwC Worldwide Tax Summaries · checked 2026-10-19The standard VAT rate is 21%, and certain supplies such as groceries, medicines and hotel accommodation are taxed at 12% from 1 January 2024.
Domestic supplies.PwC Worldwide Tax Summaries · checked 2026-10-19Companies seated in the Czech Republic must register for VAT once turnover exceeds CZK 2 million in a calendar year, and become VAT payers immediately if turnover exceeds CZK 2,536,500.
Czech-seated companies.PwC Worldwide Tax Summaries · checked 2026-10-19The Czech Republic applies the Pillar Two income inclusion rule and a 15% qualified domestic minimum top-up tax from 31 December 2023, and the undertaxed payments rule from 31 December 2024.
Groups within the global minimum tax rules.PwC Worldwide Tax Summaries · checked 2026-10-19A 60% windfall tax surcharge applied to excess profits of large banks and energy companies for 2023 to 2025.
Large banks and energy sector companies only.PwC Worldwide Tax Summaries · checked 2026-10-19A single application at the trade licensing office can include registration with the tax office for all taxes except excise and some environmental taxes.
One-stop registration.CzechInvest (fact sheet hosted by the Ministry of Foreign Affairs, mzv.gov.cz) · checked 2026-10-19Read the full guide: Tax, accounting and statutory reporting
Scope
Key questions
If your work involves another country or another area of expertise, WONE Global brings in the right professional and keeps all advisers informed.
Also in the Czech Republic
Appointed services show their named professional. Open positions link directly to the Expression of Interest form.
Cases
The cases this service leads or joins, each with what is at stake, how WONE Global handles it and who handles it in the Czech Republic.
WONE Global Intelligence
Ask in your own words. Answers come from WONE Global's checked records, with every source shown, and end with the named Partner who can act. Go deeper on any point, or build a decision file.
Contact WONE Global
Save your questions, decisions and WONE activity in one account.
Forgot your password? Reset it securely.
Partner workspaces are for Partner firms. Explore partnership →